

Blogs
Clinical Mass Spectrometry Market: Why 9.35% CAGR and LC-MS Dominance Redefine Growth
By PW Consulting, 2026-09-21
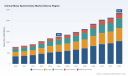
The Clinical Mass Spectrometry Market: Strategic Trends and Commercial Opportunities Through 2032
Market Status and Core Challenges
The clinical mass spectrometry market has transitioned from a specialized scientific instrument segment into a mainstream clinical diagnostic modality over the past half-decade. Market valuation moved from approximately 785.0 million USD in 2020 to 1260.0 million USD in 2025, representing a compound annual growth rate of roughly 8.2 percent across the historical window. Current trajectory models indicate expansion to 1346.99 million USD in 2026 and continued acceleration toward 2360.0 million USD by 2032, with a forecast-period CAGR of 9.35 percent. This growth profile reflects a market that has crossed the chasm from research-grade adoption into routine clinical workflows, driven by the superior specificity and multiplex capability of mass-based quantification compared with traditional immunoassays.
The regional distribution of demand reveals a mature anchor in North America, which accounts for the largest revenue share at 562.22 million USD, followed by Europe at 319.65 million USD and Asia Pacific at 234.95 million USD. Latin America and the Middle East and Africa together represent a combined base of 143.18 million USD, signaling early-stage penetration with substantial room for expansion as healthcare infrastructure and reimbursement frameworks mature. By technology type, liquid chromatography-mass spectrometry dominates installed value at 801.16 million USD, while gas chromatography-mass spectrometry holds 212.76 million USD and matrix-assisted laser desorption/ionization time-of-flight contributes 198.12 million USD, with other modalities rounding out the remainder. Across applications, therapeutic drug monitoring represents the largest clinical use case at 555.11 million USD, newborn screening follows at 315.55 million USD, and hormonal testing, hemoglobin testing, and other indications collectively account for the balance. The market remains moderately concentrated, with the top three players capturing 52.0 percent of revenue and the top five holding 62.0 percent, a structure that preserves room for differentiated entrants while rewarding scale incumbents.
Despite the favorable growth backdrop, the industry faces three structural challenges that will define capital allocation and product strategy in the near term.
Challenge 1: The Complexity-Reimbursement Gap
Mass spectrometry delivers analytical performance that routine immunoassays cannot match, but that performance often carries operational complexity that limits throughput and increases per-test cost. Many clinical laboratories still treat mass spectrometry as a specialized, limited-access service requiring highly trained operators, dedicated sample preparation, and careful method validation. When reimbursement structures do not commensurately reward this complexity, laboratories hesitate to expand mass-based panels, and manufacturers face pressure to simplify platforms without sacrificing analytical rigor. The gap between what the technology can do and what payers and laboratory economics will sustain remains the central friction point in market expansion.
MALDI-TOF Mass Spectrometer Market
Challenge 2: Regulatory Fragmentation Across Indications and Jurisdictions
Clinical mass spectrometry spans diverse indications, each with distinct evidentiary requirements, validation expectations, and regulatory pathways. A system cleared for microorganism identification does not automatically translate into a cleared workflow for therapeutic drug monitoring or hormone quantification. This fragmentation slows portfolio scale-up, increases time-to-market for new assays, and creates uneven competitive advantages across regions. Companies that can navigate a multi-indication, multi-jurisdiction regulatory landscape more efficiently than peers will capture disproportionate share in high-value applications.
Challenge 3: Workflow Integration and Standardization
As clinical mass spectrometry moves from reference laboratories into decentralized hospital and multi-site networks, standardization becomes a binding constraint. Variability in sample handling, chromatography conditions, ionization performance, and data interpretation can undermine comparability across sites and erode confidence in results. The market is increasingly rewarding vendors that offer integrated hardware-software-reagent systems, simplified operator interfaces, and traceable quality controls, while penalizing those that require extensive in-house method development for routine testing.
Key Drivers of Market Change
Technological Innovation and the Push Toward Automation
The most consequential technical shift is the move from manually intensive, laboratory-developed workflows toward automated, integrated platforms that reduce operator dependence and improve reproducibility. Quantitative software suites purpose-built for clinical analysis now accompany single quadrupole and tandem mass spectrometry systems, enabling biomarker verification, precision medicine workflows, and routine quantification with less hands-on intervention. In microorganism identification, software and sample handling innovations are compressing turnaround time and improving the reliability of organism differentiation directly from clinical specimens. These advances directly address the complexity-reimbursement gap by making high-performance mass spectrometry more compatible with high-volume clinical operations.
A concrete illustration of this trajectory is the broad expansion of reagent and assay menus on automated clinical mass spectrometry platforms. Recent milestones include CE Mark approval for an antibiotics drug monitoring reagent pack that broadens an automated mass spectrometry menu to 39 tests covering immunosuppressants, antibiotics, steroids, and vitamin D metabolites. In parallel, regulatory classification progress has lowered operational barriers: steroid assays for mass spectrometry have been classified as moderate complexity under CLIA, which expands the population of laboratories and operators able to run these tests without specialized staffing. Together, these developments demonstrate how regulatory easing and workflow automation can unlock routine clinical access for assays that previously required limited, expert-run environments.
Regulatory and Reimbursement Environment as an Accelerant and a Gatekeeper
Regulatory and coding dynamics are reshaping the commercial landscape for clinical mass spectrometry on two fronts. On the access side, moderate-complexity classification for selected mass spectrometry assays is expanding the addressable laboratory base by removing the requirement for highly specialized operators in routine settings. On the coding side, revisions to CPT codes for mass spectrometry-based testing are influencing reimbursement mechanics. Updated codes such as CPT 82542 for quantitative column chromatography/mass spectrometry reflect ongoing efforts to align coding with current practice, while reimbursement continues to vary by payer and analyte. For manufacturers and laboratory customers alike, the direction of travel matters: clearer, more predictable coding and broader complexity allowances reduce adoption friction, but analyte-specific reimbursement variability still demands careful health-economic justification for each test menu.
These dynamics also create a differentiated advantage for companies that pursue regulatory clearance proactively across multiple indications and regions. A vendor that secures clearance for therapeutic drug monitoring reagents, hormone panels, and microorganism identification systems in sequence can cross-sell across clinical departments, increase installed-base stickiness, and establish reference standards that competitors must match. The regulatory environment is thus not merely a compliance backdrop; it is increasingly a competitive moat.
Demand-Side Shifts in Clinical Practice and Patient Management
Clinical demand is being reshaped by three interrelated forces. First, precision medicine workflows are increasing the need for accurate quantification of biomarkers, drug concentrations, and metabolic markers that mass spectrometry is uniquely suited to measure. Second, the management of complex medication regimens, including antibiotics and immunosuppressants, is driving sustained demand for therapeutic drug monitoring in hospital and specialty settings. Third, early detection programs and screening protocols, including newborn screening, continue to provide a stable and high-volume demand base that rewards throughput, reliability, and standardized workflows.
At the same time, healthcare delivery is shifting toward consolidated networks and standardized testing protocols. Larger laboratory systems are seeking platforms that can support multiple indications on a single instrument footprint, reduce training burden, and provide traceable quality controls across sites. This demand-side consolidation is pushing vendors toward modular, software-centric architectures and multi-test menus, and away from single-application, laboratory-developed approaches that are difficult to scale across a health system.
PW Consulting
Supply Chain and Cost Structure Evolution
Cost structure is becoming a more explicit competitive variable as installed bases grow and laboratories compare total cost of ownership across platforms. The economics of clinical mass spectrometry depend not only on instrument price but on reagent costs, consumables durability, calibration frequency, service coverage, and the labor required to maintain compliance. Vendors that can reduce per-test operating cost through automation, longer calibration intervals, integrated reagents, and remote diagnostics are increasingly favored in procurement decisions, particularly in cost-sensitive environments.
Supply chain resilience is also under scrutiny. Platforms that reduce dependence on highly customized sample preparation steps and that offer standardized reagent packs tend to be more resilient to staffing volatility and consumable supply disruptions. As a result, the market is rewarding designs that prioritize workflow robustness and predictable consumable economics over maximal analytical flexibility alone.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
Thermo Fisher Scientific continues to anchor its strategy in quantitative clinical analysis and precision medicine workflows. Its LCQUAN quantitative software paired with ISQ EM/EC single quadrupole LC-MS systems is positioned for quantitative clinical analysis, biomarker verification, and precision medicine applications. The strategic emphasis is on software-driven quantification and a platform that supports accurate routine workflows and biomarker work, appealing to laboratories that want a credible quantitative foundation with room to extend into precision medicine use cases.
Waters Corporation leans into therapeutic drug monitoring and biomarker applications with its MassTrak LC-MS/MS platform and related solutions. A distinguishing element is the availability of FDA-cleared systems for TDM and biomarker workflows, which directly addresses the regulatory-access driver in the market. This clearance-centric approach is strategically important because it shortens the path for laboratories seeking validated, regulatorily recognized workflows rather than building laboratory-developed methods from scratch.
Bruker Daltonics differentiates through microorganism identification and differentiation, with MBT Compass HT CA software, MBT FAST Shuttle US IVD, and clinical microorganism mass spectrometry systems. The FDA clearance of its microorganism identification and differentiation system as Class II under special controls formalizes a regulatory pathway and supports adoption in clinical microbiology workflows. Bruker's positioning reflects the value of a focused application with clear clinical identity, which can be expanded within microbiology departments and integrated with broader laboratory information systems.
Roche Diagnostics International AG is pursuing a broad multi-indication IVD strategy on an automated clinical mass spectrometry platform. Its cobas Mass Spec solution with Ionify reagent packs spans therapeutic drug monitoring for antibiotics, steroid hormones, and vitamin D metabolites, supported by the Cobas i601 analyzer and an expanding IVD menu. The strategic signal is clear: Roche is using automation, a wide test menu, and regulatory milestones to position mass spectrometry as a routine clinical workhorse rather than a niche specialty tool.
Market Evolution: Consolidation, Differentiation, and New Entrants
The competitive landscape is evolving along three vectors. First, consolidation pressure is rising among scale incumbents that can cross-sell across applications and leverage installed bases to lower service and consumable costs. The top-three concentration near 52.0 percent and top-five near 62.0 percent indicates that leading players already hold meaningful share, but the remaining 38.0 percent is large enough to support specialized entrants with differentiated applications or regional strengths.
Second, differentiation is shifting from raw analytical capability toward integrated, regulatory-cleared, workflow-friendly solutions. In this environment, a vendor's ability to deliver cleared assays, simplified operator experience, and multi-test menus on a single platform is becoming as important as instrument performance alone. This favors companies that can orchestrate hardware, software, reagents, and regulatory clearance as a unified clinical solution.
Third, new entrants and regional players are finding openings in specific applications or geographies. Lower-concentration regions such as Latin America and the Middle East and Africa present early-stage demand where localized service, pricing, and workflow simplicity can be decisive. Similarly, application niches with clear clinical identity and regulatory clarity, such as microorganism identification or antibiotic TDM, can support focused entrants who build depth rather than breadth.
Future Trends and Commercial Opportunities
Trend 1: Routine Clinical Access Will Expand as Complexity Barriers Lower
Over the next three to five years, regulatory classification progress and automation will continue to broaden the laboratory base able to run mass spectrometry assays. Moderate-complexity classification for selected steroid and other assays is an early indicator of a broader shift toward routine access. The commercial opportunity lies in panels and platforms that can scale across diverse laboratory types without requiring specialized operators, supported by clear coding pathways and defensible health economics. Vendors and laboratory customers that invest early in these accessible workflows will capture utilization before the market consolidates around a smaller set of standardized platforms.
Trend 2: Multi-Indication, Software-Centric Platforms Will Become the Default Architecture
Healthcare systems increasingly prefer platforms that support multiple indications on one footprint with consistent software, quality controls, and data management. This favors architectures that separate application expansion from hardware replacement, allowing laboratories to add tests through software and reagent updates rather than capital upgrades. The commercial opportunity is for vendors that can package multi-test menus, traceable QC, and integration with laboratory information workflows as a cohesive solution, while laboratory buyers can reduce capital intensity and standardize operations across departments.
Worldwide High Resolution Mass Spectrometry System Market
Trend 3: Therapeutic Drug Monitoring and Steroid/Immunosuppressant Panels Will Remain Central Growth Engines
Therapeutic drug monitoring is already the largest application segment, and the strategic rationale is strong: managing antibiotics, immunosuppressants, and steroid-related markers requires precise quantification with clinical turnaround that mass spectrometry can provide. As automated reagent packs and cleared workflows expand, these panels can move from specialized use into more routine hospital and specialty settings. The commercial opportunity lies in full-panel strategies that bundle antibiotics, steroids, immunosuppressants, and vitamin D metabolites around a single platform, creating cross-department utilization and stronger laboratory retention.
Risks and Uncertainties
Several risks temper the outlook. Reimbursement variability by payer and analyte can slow adoption for specific tests even when analytical performance is strong. Regulatory timelines and classification outcomes remain uncertain across indications and regions, meaning portfolios that depend on a single clearance event face concentration risk. In addition, if automation and software do not deliver the expected reduction in operating cost and training burden, the complexity-reimbursement gap will persist and limit throughput gains. Finally, coding and reimbursement updates can shift the economics of specific assays, requiring continuous health-economic monitoring rather than one-time justification.
Strategic Recommendations for Decision Makers
For Manufacturers and Platform Providers
- Prioritize integrated, software-centric architectures that allow multi-test expansion without hardware replacement, and pair them with cleared or clearly regulatory-tracked workflows for high-value indications such as TDM, steroid panels, and microorganism identification.
- Design for operational simplicity and total cost of ownership, not just analytical performance. Reduce training burden, automate sample preparation where feasible, and offer predictable reagent and calibration economics to win procurement decisions in consolidated laboratory networks.
- Build multi-indication, multi-region regulatory strategies in advance. Early and sequential clearances across applications and jurisdictions can become a defensible competitive moat and accelerate cross-sell within health systems.
For Investors and Strategic Partners
- Focus on companies that convert regulatory and workflow advantages into installed-base growth and recurring consumable revenue, particularly where moderate-complexity classification, cleared assays, and broad test menus expand the addressable laboratory base.
- Evaluate exposure to reimbursement and coding risk at the analyte level. Investments tied to panels with clearer coding pathways and stronger health-economic support are less exposed to reimbursement variability than narrow, single-test offerings.
- Watch for consolidation opportunities in regional markets where service capability, pricing, and workflow simplicity matter more than cutting-edge analytical novelty. Localized execution can be a durable advantage in earlier-stage regions.
For Procurement and Laboratory Decision Makers
- Evaluate platforms based on total cost of ownership, regulatory status of assays, and the ability to standardize across multiple indications and sites, rather than instrument specifications alone. A platform that supports several cleared panels with integrated QC and data management can reduce operational risk and capital intensity.
- Assess training burden, staffing resilience, and service coverage as part of the sourcing decision. Workflows that lower dependency on specialized operators and offer predictable maintenance are better suited to high-throughput environments and decentralized networks.
- Monitor coding and reimbursement developments for the specific analytes you plan to run, and align test menu expansion with clear reimbursement pathways and health-economic justification to avoid adoption friction later.
The clinical mass spectrometry market is moving from specialist adoption to routine clinical integration, and the winners will be those who align analytical performance with workflow simplicity, regulatory clarity, and defensible economics. For decision makers who need granular segmentation, region-by-region dynamics, per-application growth drivers, and customized strategic scenarios, a detailed research report can provide the depth required to translate these trends into concrete plans. To access the full segmentation breakdown, competitive benchmarking, and tailored recommendations, request the complete PW Consulting report on the Clinical Mass Spectrometry Market.
For detailed analysis of this topic, please visit the official page: Clinical Mass Spectrometry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tax Software Market: Why Cloud Adoption and 9% CAGR Shift the Competitive Landscape
By PW Consulting, 2026-09-21
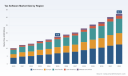
Navigating the Tax Software Market: Strategic Trends and Commercial Opportunities
The global tax software market is undergoing a structural transformation driven by technological advancement, regulatory complexity, and shifting user expectations. Valued at approximately $17.6 billion in 2025, the market has expanded steadily from $10.2 billion in 2020, reflecting a compound annual growth rate of 9.0 percent through 2032. By the end of the forecast horizon, total market revenue is projected to approach $32.3 billion, underscoring sustained institutional and consumer demand for digital tax solutions. This growth trajectory is not merely a function of population expansion or inflation; it represents a fundamental shift in how tax compliance, reporting, and advisory services are delivered. Organizations that understand the underlying drivers, competitive dynamics, and emerging friction points will be best positioned to capture value in the coming years.
Market Landscape and Core Challenges
The market's expansion has been broad-based, with cloud-based solutions now representing the largest share of revenue, reflecting a decisive migration away from legacy on-premises deployments. Individual tax filing continues to anchor volume, while business and corporate tax management segments contribute meaningful but more specialized revenue streams. Geographically, adoption patterns vary significantly, with mature markets showing high penetration and emerging regions accelerating digital onboarding as regulatory frameworks modernize and internet infrastructure improves.
Despite the favorable growth backdrop, the industry faces several structural challenges that will shape competitive outcomes over the next five years. First, regulatory fragmentation and compliance velocity are intensifying. Tax authorities across jurisdictions are updating filing formats, validation rules, and electronic submission requirements at an accelerating pace. Software vendors must continuously align their platforms with IRS Modernized e-File standards, state-level franchise tax mandates, and error-checking protocols. The operational burden of maintaining compliance across multiple jurisdictions creates a high barrier to entry and rewards vendors with robust regulatory monitoring and rapid update cycles.
Second, user experience expectations are rising faster than legacy architectures can accommodate. Both individual filers and professional preparers increasingly expect intuitive interfaces, guided workflows, automated data ingestion, and real-time error feedback. Platforms that rely on manual form entry or fragmented dataflows risk losing adoption to solutions that reduce cognitive load and accelerate filing turnaround. This shift is particularly pronounced among self-employed professionals and small business owners who prioritize simplicity and predictable pricing.
Third, cost structure pressures are reshaping procurement decisions. Professional-grade tax software typically carries annual licensing costs in the range of $700 to $1,275 for multi-user access, a meaningful expense for smaller firms and independent preparers. While these investments deliver compliance assurance and workflow efficiency, margins remain sensitive to pricing models, update frequency, and the perceived value of advanced features. Vendors must balance feature richness with affordability, particularly as free or low-cost guided filing options expand for eligible taxpayers and raise expectations for baseline functionality across the market.
These challenges intersect at a critical inflection point: the market is moving from a compliance-centric model toward an experience- and outcomes-centric model. The winners will be those that convert regulatory complexity into simplified user journeys, maintain update reliability at scale, and deliver clear return on investment for both professional firms and end users.
Key Drivers Shaping Market Evolution
Several interconnected forces are accelerating demand and redefining value propositions across the tax software ecosystem.
Technological Innovation and Workflow Automation
Cloud-native architectures, automated form population, and integration with financial data sources are reducing manual effort and error rates. Guided preparation workflows, predictive error checks, and rapid e-filing feedback loops are becoming table stakes rather than differentiators. For professional preparers, annual software updates that incorporate new tax laws, form revisions, and validation enhancements are essential to maintaining throughput and compliance accuracy. The release cadence and update transparency of leading platforms directly influence user retention and referral momentum within accounting and tax practices.
Policy and Regulatory Environment
Regulatory modernization is both a constraint and a catalyst. Tax authorities are progressively mandating electronic submissions, enhanced error validation, and structured data formats to improve processing efficiency and reduce rejection rates. Providers must demonstrate compliance with assurance testing systems and maintain approved status to operate within official filing channels. At the same time, tiered access models, such as no-cost guided preparation for eligible income brackets, expand the addressable user base while pressuring vendors to offer clear differentiation for premium features. The net effect is a more standardized compliance baseline, with competitive advantage shifting toward usability, advisory extensions, and multi-jurisdiction coverage.
Demand-Side Behavior Shifts
End users are increasingly treating tax software as an annual operating tool rather than a one-time filing utility. Individuals and small business owners value continuity, data portability, and time savings. Professional firms seek platforms that scale across seasons, support diverse client profiles, and integrate with broader practice management workflows. The preference for cloud delivery amplifies these expectations by enabling remote access, collaborative preparation, and centralized document management. As a result, switching costs are rising for users who have invested in historical data, trained workflows, and integrated ecosystems, favoring vendors that can deepen lifetime value through reliability and extensibility.
Cost Structure and Procurement Dynamics
The economics of tax software procurement are evolving as firms weigh licensing fees against labor costs, error remediation, and seasonal capacity constraints. Multi-user access models, update subscriptions, and support expectations shape total cost of ownership. For smaller practices, predictable annual pricing and straightforward update processes can be decisive, while larger firms prioritize scalability, role-based access, and audit-ready documentation. The market is gradually rewarding vendors that offer transparent pricing, efficient update delivery, and demonstrable time savings, particularly in environments where preparer labor remains a significant cost driver.
Competitive Landscape and Leading Strategies
The market is characterized by a concentrated core of established vendors alongside a long tail of specialized providers serving distinct user segments. Intuit maintains a prominent position in the individual and self-employed segments, leveraging broad brand recognition, guided filing experiences, and a wide distribution footprint. H&R Block complements this landscape with a strong retail and digital presence, emphasizing accessible filing pathways and small business support. In the professional segment, Wolters Kluwer and Thomson Reuters serve accounting firms and tax practitioners with comprehensive preparation and practice management tools, focusing on regulatory update cadence, multi-form coverage, and workflow integration. Smaller but focused providers, including Drake Software, TaxAct, TaxSlayer, On-Line Taxes, CFS Tax Software, and Advanced Tax Solutions, differentiate through niche functionality, pricing clarity, or specialized professional workflows.
Accounting Software Market
Strategic differentiation is increasingly defined by three dimensions: compliance reliability, user experience, and ecosystem fit. Leading vendors invest heavily in maintaining approved e-filing status, delivering timely updates aligned with tax law changes, and providing error validation that reduces rework. Equally important is the design of preparation workflows, including guided prompts, document capture, and transcript integration that lower the skill threshold for complex filings. Finally, ecosystem fit matters as firms evaluate how well a platform aligns with existing practice management, client communication, and data storage preferences. Vendors that excel across all three dimensions tend to retain multi-year loyalty, while laggards face churn when competitors demonstrate faster update cycles or smoother user journeys.
The competitive landscape is evolving through both consolidation and fragmentation. Larger platforms are expanding their feature sets to serve adjacent user segments, blurring the line between individual and professional tools. At the same time, specialized providers continue to carve out defensible positions by focusing on specific form sets, regional compliance requirements, or price-sensitive professional markets. New entrants face a steep climb given the importance of approval status, historical data accumulation, and trusted update cycles, but they can gain traction by targeting underserved workflows, offering transparent pricing, or delivering superior onboarding experiences. Overall, the market is moving toward a bifurcated structure in which broad-platform leaders compete on scale and integration while focused providers compete on specificity and cost clarity.
PW Consulting
Future Trends and Commercial Opportunities
Looking ahead to the next three to five years, three trends are likely to determine where value concentrates and how competitive advantage is built.
Trend One: Compliance-as-a-Service and Continuous Update Models
Regulatory change will continue to accelerate, and the ability to deliver reliable, audited updates will become a core commercial asset. Platforms that institutionalize continuous compliance monitoring, automated test suites, and rapid deployment pipelines will reduce the risk of filing rejections and user friction. This trend creates opportunities for vendors to monetize update assurance, compliance documentation, and proactive regulatory alerts as part of premium service tiers. For buyers, the commercial implication is clearer visibility into total compliance risk and a stronger basis for vendor selection based on update reliability rather than feature count alone.
Trend Two: Guided Experiences and Tiered Offerings
User expectations will keep shifting toward guided, low-friction preparation, particularly among individuals and small business owners who value speed and certainty. Tiered pricing models will likely deepen, with no-cost or low-cost guided pathways for eligible users coexisting alongside premium advisory and comprehensive preparation features. Vendors that design seamless handoffs between free, guided, and professional-grade workflows can expand reach while preserving margin through upsell into data continuity, multi-state filing, and practice-oriented tools. The strategic opportunity lies in using guided experiences as an entry point that builds trust and historical data retention, then converting that engagement into recurring, higher-value relationships.
Worldwide Tax & Revenue Collection Software Market
Trend Three: Integration with Broader Financial Workflows
Tax preparation is increasingly viewed as one node within a larger financial operations workflow. Connections to accounting data, bank and payment records, payroll information, and document storage reduce duplicate entry and improve accuracy. Platforms that enable secure data exchange, standardized imports, and role-based collaboration will capture additional stickiness and reduce seasonal onboarding costs. This trend opens commercial pathways for vendors to position tax software as part of a year-round financial toolkit, rather than a seasonal utility, potentially expanding cross-sell opportunities and lengthening the customer lifecycle.
These trends carry inherent uncertainties. Regulatory decisions can alter filing requirements or reimbursement structures, shifting demand patterns unexpectedly. Rapid update cycles can strain support resources if error validation or form coverage is incomplete. Pricing pressure from free or low-cost guided options may compress margins in volume-driven segments. And integration ambitions can collide with data privacy expectations and interoperability constraints. Organizations that monitor these variables closely and maintain flexible product roadmaps will be better equipped to pivot as conditions evolve.
Strategic Actions for Decision Makers
The following recommendations are intended to help different stakeholder groups translate market dynamics into practical actions.
For Software Vendors and Product Leaders
Prioritize update reliability and compliance assurance as foundational differentiators. Invest in automated testing, transparent release notes, and rapid remediation processes to reduce filing rejections and user friction. Simultaneously, refine user journeys to lower the cognitive burden of complex forms, and design tiered offerings that preserve accessibility while creating clear paths to premium features. Evaluate integration points with accounting, document management, and client communication tools to strengthen year-round relevance and reduce seasonal switching risk.
For Investors and Strategic Allocators
Focus due diligence on vendors with durable update cycles, approved filing status, and evidence of user retention beyond a single season. Assess whether a company's pricing model aligns with the cost sensitivities of its target segment, and whether its roadmap anticipates regulatory complexity rather than reacting to it. Favor platforms demonstrating clear product-led growth signals, such as multi-year data continuity, expanding form coverage, and measurable time savings for professional preparers. Monitor consolidation potential among specialized providers whose workflows could be absorbed into broader platforms.
For Procurement Teams and Practice Owners
Evaluate tax software based on total compliance risk, update cadence, and workflow fit rather than headline pricing alone. Ask vendors how they validate form changes, how quickly updates reach users, and how error feedback is delivered during filing windows. Consider the long-term value of data portability, role-based access, and integration with existing practice tools. Where eligible, explore guided filing options to reduce preparation time for straightforward returns, while reserving professional-grade platforms for complex cases that require multi-state coverage, entity-level filings, or advisory extensions.
Market conditions in tax software are being reshaped by the intersection of regulatory modernization, cloud adoption, and rising user expectations. The organizations that thrive will be those that treat compliance reliability as a product foundation, design for sustained user engagement, and position their offerings within broader financial workflows. Detailed segmentation data, vendor scorecards, regional demand patterns, and customized strategic recommendations are available in the full research report, which provides the granular evidence base needed to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Tax Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Data Center Busway Market 2026: 9% CAGR Means the Competition Just Changed
By PW Consulting, 2026-09-21
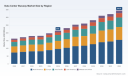
Data Center Busway Market 2025–2032: Strategic Shifts, Power Density, and the Path to Sustainable Scalability
The data center busway market has entered a phase of accelerated structural transformation, driven by the convergence of artificial intelligence workloads, hyperscale expansion, and evolving power distribution requirements. Valued at approximately USD 215.0 million in 2025, the market has grown from USD 163.15 million in 2020, reflecting a compound annual growth rate of 9.0 percent across the forecast horizon through 2032, when revenues are projected to reach USD 344.8 million. This trajectory is not merely a function of incremental capacity additions. It reflects a fundamental rethinking of how power is routed, tapped, and managed within increasingly dense and modular computing environments. For executives, investors, and procurement leaders, the busway segment represents both a direct response to next-generation infrastructure demands and a lens through which broader shifts in data center design, material economics, and regulatory compliance can be understood.
The market’s expansion has been relatively consistent in recent years, yet the composition of growth is shifting. Historical performance from 2020 to 2025 illustrates steady upward movement, with particular acceleration in the most recent intervals as AI-driven deployment cycles matured. The forward outlook suggests that the pace will be sustained, though not uniformly distributed across all end-use contexts or product configurations. Rather than treating busway systems as commoditized electrical distribution components, industry participants are increasingly positioning them as integral elements of high-density, rapidly deployable, and energy-aware data center architectures. This reframing is reshaping competitive dynamics, procurement criteria, and long-term investment theses.
Market Landscape and Core Challenges
The current market environment is characterized by robust demand signals, but also by structural frictions that will define competitive outcomes over the next several years. Three intersecting challenges stand out as particularly consequential for operators, suppliers, and capital allocators alike.
Power Density and Architectural Compression
The transition toward high-density computing environments is compressing traditional layout assumptions. As rack power densities increase and AI clusters demand higher amperage distribution, legacy cable-based or fixed-tray approaches are encountering spatial, thermal, and installation constraints. Busway systems are gaining relevance because they offer modular tap-off flexibility, shorter deployment cycles, and the ability to adapt to evolving white-space configurations. However, this shift is not automatic. Integrating high-ampacity busway into prefabricated or containerized data center pods requires coordinated engineering across power, cooling, and structural dimensions. The challenge for suppliers is to deliver systems that balance current-carrying capacity, footprint efficiency, and ease of modification without introducing complexity that undermines the very speed advantages busway is meant to provide.
Material Cost Volatility and Conductor Selection
Raw material dynamics are becoming a more prominent factor in busway economics. Copper prices moved to 15-month highs in 2025 amid supply disruptions and sustained data center demand, placing upward pressure on manufacturing costs for copper-dependent systems. At the same time, aluminum conductor options are gaining attention for their weight and installation labor advantages in high-density deployments. This creates a strategic tension: copper remains the default expectation for many mission-critical specifications, while aluminum-based designs can reduce weight and installation effort when properly engineered and certified. Manufacturers and procurement teams must navigate performance expectations, total installed cost, and long-term reliability rather than relying on material conventions alone.
PW Consulting
Regulatory and Compliance Pressures
Regulatory expectations are increasingly shaping infrastructure upgrade decisions. In Europe, the Energy Efficiency Directive has drawn attention to the need for data center operators to modernize infrastructure, including busway replacement and upgrades in certain contexts, to support compliance objectives. In parallel, safety and reliability expectations in mission-critical facilities continue to elevate the importance of certified solutions. For example, UL listing requirements for specific busway offerings have become a meaningful differentiator for operators seeking assured reliability in data center applications. These dynamics do not simply add cost; they reshape the value proposition of busway systems by linking power distribution decisions to broader energy, safety, and operational resilience goals.
Key Drivers Reshaping the Market
The growth trajectory of the data center busway market is being propelled by a set of reinforcing drivers that extend beyond simple capacity expansion. Understanding how these forces interact is essential for anticipating where demand will concentrate and which product strategies will gain traction.
Technology Innovation in High-Ampacity, Modular Distribution
Product development is increasingly focused on scalable, high-current busway architectures that can adapt to rapidly changing white-space layouts. One of the most notable shifts is the move toward systems capable of supporting amperage levels well beyond conventional server room distributions, including solutions designed for environments where high-ampacity busway systems exceeding 4000A are required. This trend is closely tied to hyperscale AI data center construction, where power distribution must accommodate dense compute clusters while preserving flexibility for future expansion.
Innovation is also evident in toolless tap-off designs, double-stack configurations, and integrated monitoring capabilities. Double-stack busway systems, for instance, are being introduced to support growing AI data center demands while preserving white space, effectively enabling higher power density without proportionally increasing the floor footprint. At the same time, modular plug-in tap designs are reducing installation friction and enabling faster reconfiguration as workloads evolve. These advances are not isolated product features; they collectively support a broader architectural shift toward busway as a dynamic distribution layer rather than a static electrical accessory.
AI-Driven Demand and Hyperscale Deployment Patterns
The most powerful demand-side force is the proliferation of AI-focused infrastructure. Hyperscale AI data center construction is driving demand for high-ampacity busway systems, particularly in environments where power distribution must scale in lockstep with accelerated compute density. This is altering procurement priorities: speed of deployment, modularity, and compatibility with prefabricated modules are increasingly valued alongside raw current-carrying capacity.
The trend is visible in recent product and exhibition activity. New EcoStruxure Pod Data Center solutions have been introduced with high-power busway integrated alongside liquid cooling and prefabricated modules for AI cluster deployments, illustrating how busway is being embedded into broader pod-level architectures. Similarly, scalable high-capacity double-stack track-style busway systems have been announced to address growing AI data center demands while preserving white space. At major industry gatherings, multiple manufacturers have showcased modular data center solutions that emphasize busway power distribution as a core element of next-generation AI infrastructure. These developments suggest that busway is no longer a peripheral consideration; it is becoming a defining component of AI-ready data center design.
Policy, Efficiency Mandates, and Certification-Driven procurement
Policy and regulatory frameworks are influencing both retrofit and greenfield decisions. Efficiency mandates and energy-related directives are pushing operators to evaluate infrastructure upgrades more holistically, including busway replacement where it contributes to compliance or operational improvement. At the same time, certification and listing requirements are becoming more salient in procurement processes for mission-critical facilities. This is especially relevant where reliability, safety, and interoperability must be demonstrable through recognized standards.
The practical effect is a more discerning buyer environment. Operators are not simply seeking the lowest upfront cost; they are increasingly weighing lifecycle performance, compliance readiness, and integration with broader facility systems. For suppliers, this means that product leadership is increasingly defined by the ability to provide certified, monitored, and easily integrated solutions rather than by volume alone. In this context, busway systems that combine protection, metering, monitoring, and modular tap-off functionality are well positioned to align with evolving procurement criteria.
Supply Chain and Cost Structure Considerations
Supply chain conditions and material economics continue to shape product strategy and pricing dynamics. Copper price movements have introduced cost variability that affects both manufacturers and end users, particularly in segments where copper remains the dominant conductor choice. This has reinforced interest in aluminum conductor options, which can reduce weight and installation labor in high-density deployments. The strategic implication is that conductor selection is becoming a more explicit trade-off analysis, balancing electrical performance, mechanical handling, certification requirements, and installed cost.
In parallel, the broader supply chain emphasis on modularity and prefabrication is encouraging busway designs that can be shipped, assembled, and commissioned with minimal on-site customization. This aligns with the pace demands of hyperscale and colocation projects, where schedule certainty is often as valuable as technical performance. Suppliers that can standardize high-value configurations while maintaining flexibility for site-specific requirements are likely to capture disproportionate advantage in a market where deployment speed is a critical success factor.
Competitive Landscape and Leading Strategies
The competitive environment in the data center busway market is moderately concentrated, yet it is evolving quickly as suppliers differentiate around architecture, integration, and application-specific engineering. With a combined share held by the top three players at approximately 24.6 percent and the top five at about 26.2 percent, the market remains relatively fragmented at the top, leaving room for specialized positioning, regional strength, and targeted innovation. The strategic question is not simply who holds the largest share today, but which companies are building durable advantages in high-growth subsegments tied to AI, modularity, and compliance-driven upgrades.
Leading Players and Strategic Positioning
Several established manufacturers are defining the market’s direction through product architectures that explicitly address high-density AI workloads, modular deployment, and integrated monitoring. Their approaches illustrate how busway is being repositioned from a utility product to a strategic infrastructure component.
Schneider Electric has emphasized integrated pod-level solutions that combine high-power busway with prefabricated modules and liquid cooling for AI cluster deployments. Its recent product launch of EcoStruxure Pod Data Center solutions featuring high-power busway integrated with liquid cooling and prefabricated modules reflects a strategy centered on holistic, rapid-deployment architectures. The company’s exhibition activity has also highlighted busway integration with power shelf concepts for 48V AI systems, signaling attention to evolving power architectures as well as traditional distribution.
Eaton Corporation has focused on modular tap-off flexibility and scalable white-space optimization through track-style busway systems. Its Pow-R-Way III and PowerWave 2 platforms are positioned around modular tap-off for scalable white-space and high-density power distribution. By showcasing modular data center solutions including busway power distribution at Data Center World 2026, Eaton reinforced a strategy that aligns busway with adaptable facility layouts and repeatable deployment patterns.
Vertiv has advanced high-capacity, space-efficient designs with its PowerBar Track and double-stack busway systems. Its offerings support high current levels with copper and aluminum options and emphasize toolless tap-offs for AI data center white-space optimization. The recent announcement of a scalable high-capacity double-stack PowerBar Track busway system for growing AI data center demands illustrates a clear focus on density, scalability, and space preservation.
ABB Ltd has concentrated on integrated protection, metering, and monitoring within low-voltage busway systems for server room distribution. Its Lmax-T systems are designed to support data center server room distribution with integrated protection, metering, and monitoring up to 86 kW per rack. This positions ABB around operational visibility and localized power management, which is increasingly valued in environments where granular monitoring supports efficiency and reliability objectives.
Siemens AG has pursued smart monitoring and strategic power distribution partnerships, with aluminum-based busway systems designed for high-density AI data centers. Its approach underscores the growing importance of monitoring-enabled systems and collaborative ecosystem positioning in high-value segments.
LS Cable & System has built a differentiated presence around modular plug-in taps and UL listing for high-capacity AI and energy-efficient data center power distribution. Its Data-way™ busway with modular plug-in taps and UL listing emphasizes mission-critical reliability and readiness for next-generation AI data centers, a positioning reinforced by its exhibition presence at Data Center World 2026.
Other notable participants contribute additional variety to the competitive field. Legrand offers data center busway solutions for modular power distribution in mission-critical facilities. nVent provides custom medium- and high-voltage bus systems for industrial and data center power applications, expanding the scope beyond standard low-voltage distribution. EAE Electric offers busway systems up to 6300A with data center-specific solutions for power distribution, highlighting the persistent demand for very high-current configurations in specialized environments.
Strategic Differentiation and Evolving Market Structure
Across these players, differentiation is increasingly rooted in four dimensions: current capacity and conductor flexibility, modularity and deployment speed, integration with monitoring and protection, and certification or listing readiness for mission-critical use. Companies that can combine these attributes within repeatable, prefabrication-friendly architectures are gaining leverage in a market where AI-driven projects reward both performance and schedule certainty.
The market structure appears likely to evolve through a mix of consolidation, specialization, and ecosystem positioning rather than through a single dominant wave of unification. Large, globally integrated suppliers benefit from breadth, engineering resources, and cross-selling potential across power management portfolios. At the same time, specialized or regionally strong players can compete effectively by emphasizing certification, customized high-current solutions, or rapid responsiveness to local procurement requirements. New entrants and adjacent players may also find openings by targeting specific niches such as very high-ampacity systems, aluminum-based designs, or modular pod-integrated busway solutions. The overall trend is toward a more application-aware competitive landscape, where Winning strategies depend on how well a product aligns with the operational, regulatory, and architectural priorities of the end facility.
Future Trends and Commercial Opportunities
Looking ahead to the next three to five years, several trends are likely to shape the data center busway market and create distinct commercial opportunities. These trends are interconnected, and their combined effect will determine which product categories, geographies, and use cases capture the most value.
Trend 1: High-Ampacity, AI-Optimized Busway as a Default Consideration
As AI workloads continue to drive higher power densities, high-ampacity busway systems will become less of a specialized option and more of a baseline consideration for new hyperscale and large colocation builds. The practical opportunity lies in designing for scalability from the outset: systems that can accommodate future power increases, support modular tap expansion, and integrate with cooling and prefabricated infrastructure will command stronger interest than fixed, single-purpose configurations. Commercially, this favors suppliers that can offer proven high-current performance, conductor flexibility, and documented compatibility with AI cluster layouts. The risk is that demand may become concentrated in a narrower set of high-specification systems, intensifying competition among suppliers that can meet those requirements at scale.
Trend 2: Material Strategy and Total Installed Cost as Competitive Levers
Material economics will continue to influence product design and procurement decisions. Copper price volatility and the practical benefits of aluminum conductor options in high-density deployments will encourage more explicit total cost evaluations, including weight, handling, installation labor, and long-term maintainability. This creates an opportunity for manufacturers to differentiate through engineered solutions that justify material choices with measurable installation and operational advantages. It also introduces a risk: if certification, customer familiarity, or application-specific performance requirements strongly favor one conductor type in certain segments, the ability to substitute may be limited. The most resilient strategies will likely involve offering credible options across conductor types while clearly mapping each to specific use cases and total cost profiles.
Busway-Bus Duct Market
Trend 3: Compliance, Monitoring, and Lifecycle Value as Procurement Differentiators
Regulatory efficiency expectations and mission-critical reliability standards are likely to elevate the importance of compliance-ready, monitored busway systems. As operators align infrastructure upgrades with energy efficiency and operational resilience goals, busway solutions that incorporate protection, metering, and monitoring will be better positioned to support both compliance and operational management objectives. The commercial opportunity here extends beyond hardware sales to includes integrated value propositions that reduce lifecycle risk, support audits or reporting, and simplify future modifications. A key uncertainty is the pace and uniformity of regulatory adoption across regions, which could create uneven demand patterns and require suppliers to remain agile in different compliance environments.
Data Center Rack Market
Actionable Implications for Decision Makers
The data center busway market is evolving from a component-level discussion into a strategic infrastructure question. The following implications are most relevant for manufacturers, investors, and procurement leaders seeking to act on current dynamics rather than react to them.
For Manufacturers and Solution Providers
- Prioritize architectures that combine high-current capability with modular tap flexibility and toolless or low-friction installation, especially where AI-driven white-space optimization is a priority.
- Develop clear conductor strategies that address both copper and aluminum use cases, supported by certification, testing, and documented total installed cost arguments rather than relying on convention alone.
- Strengthen integration narratives around monitoring, protection, and prefabricated module compatibility, since these attributes increasingly align with procurement criteria for mission-critical and efficiency-focused facilities.
For Investors
- Focus on companies with credible positioning in high-ampacity, AI-related deployments and evidence of product momentum through launches, trade presence, or qualified project pipelines.
- Assess exposure to material cost dynamics and supply chain resilience, particularly where product portfolios depend heavily on a single conductor type or limited sourcing pathways.
- Look for differentiation that is difficult to replicate quickly, such as certified solutions, integrated monitoring capabilities, or strong alignment with modular/pod-based data center architectures.
For Procurement and Infrastructure Leaders
- Evaluate busway options against total lifecycle criteria, including deployment speed, reconfiguration flexibility, monitoring and protection integration, and compliance readiness, rather than basing decisions solely on initial price.
- Plan for future power density increases by specifying systems that can scale in amperage and tap capacity without requiring wholesale redesign of the distribution layer.
- Verify certification and listing status early in the selection process, especially where mission-critical reliability and regulatory alignment are explicit project requirements.
The breadth of forces shaping this market—from AI-driven power density and material economics to efficiency mandates and modular deployment models—makes detailed, up-to-date segmentation and company-level intelligence highly valuable. For decision makers evaluating market entry, capacity expansion, product roadmap priorities, or procurement strategies, a fuller view of subsegment dynamics, regional variation, and competitive movements can materially improve planning accuracy. More comprehensive data and tailored analysis are available through the complete PW Consulting market report, which provides deeper segmentation detail and customized strategic guidance for specific business contexts.
For detailed analysis of this topic, please visit the official page: Data Center Busway Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Real Drivers Behind Chlorogenic Acid’s 5.69% Growth Trajectory Through 2032
By PW Consulting, 2026-09-21
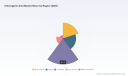
Chlorogenic Acid Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Snapshot and Core Challenges
The chlorogenic acid market has evolved from a niche botanical ingredient into a structurally important segment within the broader functional ingredients landscape. Over the past five years, the market has demonstrated steady expansion, moving from a baseline above 160 million USD in 2020 to an estimated 215 million USD in 2025. Looking ahead through 2032, the trajectory points toward continued growth, with values projected to exceed 315 million USD by the end of the forecast period. This translates to a compound annual growth rate of approximately 5.69 percent, a pace that reflects durable demand rather than a short-lived hype cycle. The growth profile suggests an ingredient that is gradually moving from specialized applications into mainstream formulations, supported by both consumer interest and formulator confidence.
Despite this favorable growth backdrop, the market faces several structural challenges that will shape how companies compete and where value is captured. First, raw material exposure remains a persistent vulnerability. Global coffee production has consistently exceeded 11 million tons, with roughly 8 million tons traded internationally and Brazil and Viet Nam accounting for nearly half of total output. This concentration creates a supply chain that is inherently sensitive to weather events, crop disease, logistics bottlenecks, and shifting trade dynamics. For chlorogenic acid processors, the consequence is not simply a pricing issue but a structural dependency on a commodity ecosystem that can swing quickly from surplus to constraint.
Second, regulatory divergence across key markets is adding complexity to formulation and market access strategies. In Europe, specific food products such as coffee substitutes have faced limits on chlorogenic acid content set below 100 mg/L, creating a compliance framework that differs materially from other regions. In the United States, chlorogenic acid is recorded as a dietary substance with no specific quantity restrictions identified in the latest database, reflecting a more permissive posture. This asymmetry means that global ingredient suppliers and finished product manufacturers must manage distinct formulation rules, documentation requirements, and labeling considerations depending on where products are sold. The regulatory gap is not necessarily a barrier to growth, but it does reward companies that can navigate multiple compliance regimes efficiently while disadvantaging those that rely on a single-market assumption.
Third, the market is entering a phase where differentiation is becoming more difficult to sustain through generic claims alone. As awareness of chlorogenic acid spreads across nutraceutical, food and beverage, cosmetics, and pharmaceutical applications, the risk increases that the ingredient becomes a commoditized specification rather than a strategic differentiator. Suppliers that compete primarily on price or broad availability may find margins compressing as the market matures. The strategic question is whether companies can build defensible positions through purity standards, clinical validation, traceability, application-specific functionality, or proprietary processing methods before the market settles into a more homogeneous competitive structure.
Key Drivers Reshaping the Market
Technological Innovation and Processing Precision
A central driver of market evolution is the maturation of extraction and purification technologies that enable higher consistency and purity levels. The ability to deliver high-purity chlorogenic acid extracts, including HPLC 98 percent grades, has shifted the ingredient from a broadly characterized botanical to a defined functional input with repeatable specifications. For formulators, that precision matters because it reduces batch-to-batch variability, supports more accurate dosing, and simplifies regulatory and quality documentation. It also creates room for premium positioning, particularly in applications where bioactive consistency is tied directly to performance claims or clinical credibility.
At the same time, extraction innovation is increasingly linked to supply security and traceability rather than purity alone. Recent capacity and sourcing expansions in key raw-material hubs have demonstrated how processors are tightening control over upstream supply chains. By strengthening relationships with producing regions and improving traceability systems, leading suppliers are attempting to reduce the risk of disruption while also reinforcing the quality narrative that premium buyers increasingly expect. This combination of technical precision and supply accountability is becoming a meaningful competitive lever, especially in applications where ingredient provenance is part of the product story.
Policy and Regulatory Environment
Regulatory dynamics are influencing both the pace and the shape of market growth. The divergence between mature markets and emerging markets means that product developers cannot assume a uniform pathway for chlorogenic acid-rich formulations. European limits in certain food categories require careful application engineering, while the U.S. posture allows more flexibility in dietary and supplement contexts. This landscape encourages companies to invest in regulatory intelligence and application-specific formulation strategies rather than treating chlorogenic acid as a universally interchangeable ingredient.
Trade policy adds another layer of influence. Recent adjustments in U.S. green coffee tariffs have begun to alter import expenditures for key producing regions, affecting cost structures and sourcing decisions for downstream processors. For companies that rely on imported green coffee beans or related botanical inputs, these shifts can affect landed costs, working capital, and the economics of regional sourcing strategies. The implication is that regulatory and trade monitoring is no longer a peripheral activity; it is becoming a strategic input into sourcing, pricing, and market-entry decisions.
Demand-Side Shifts in Consumer and Business Behavior
Demand is being shaped by a broader move toward functional wellness, metabolic health, and plant-based formulation preferences. In nutraceutical and dietary supplement contexts, chlorogenic acid is often associated with metabolic and weight-management narratives, which continue to attract consumer attention and drive product development. In food and beverage, the ingredient is increasingly evaluated for flavor-compatible functional benefits, especially in formats that seek to combine taste with a health-oriented positioning. In cosmetics and personal care, botanical actives with antioxidant and skin-care relevance continue to support interest in chlorogenic acid as part of multi-functional ingredient systems.
Importantly, the demand story is not limited to end consumers. Business buyers are increasingly asking for documented functionality, application support, and supply reliability. This shift raises the bar for ingredient suppliers. Companies that can offer more than raw material, such as formulation guidance, consistency data, and application-specific performance context, are better positioned to secure long-term contracts and defend pricing. The market is therefore rewarding suppliers that treat chlorogenic acid as part of a solutions offering rather than a standalone commodity.
Supply Chain and Cost Structure Dynamics
Cost structures in the chlorogenic acid market are influenced by a mix of agricultural supply conditions, processing complexity, and logistics. The concentration of coffee output among a small number of producing countries heightens the sensitivity of input availability to regional disruptions. When supply is tight, processors face not only higher raw material costs but also the challenge of maintaining consistent specifications. When supply is ample, competition can intensify and pricing pressure can increase, particularly for standard-grade material. This cyclicality means that effective cost management requires more than negotiating favorable purchase prices; it depends on portfolio diversification, inventory strategy, and the ability to shift between supply sources without compromising quality.
The market also benefits from diversified botanical sources beyond green coffee beans. Honeysuckle and eucommia-based inputs contribute additional supply options and can help reduce single-commodity dependency. However, the strategic use of alternative sources is not simply about substitution. It requires understanding how each source compares in terms of yield, purity potential, regulatory acceptance, and application fit. Suppliers that can integrate multiple raw material pathways with consistent processing standards are better equipped to manage volatility while preserving specification integrity.
Ellagic Acid Market
Competitive Landscape and Leading Strategies
The competitive environment in the chlorogenic acid market reflects a blend of globally established botanical ingredient specialists and high-scale producers with strong regional footprints. The market is moderately concentrated, with a meaningful share of activity captured by a limited set of leading suppliers. This concentration suggests that scale, technical capability, and supply-chain control are important determinants of competitive advantage, while also leaving room for differentiated niches in application-specific formulations and premium-grade extracts.
Naturex, part of Givaudan, illustrates a strategy centered on standardized green coffee bean extracts with strong emphasis on traceability and quality compliance. Its focus spans nutraceutical, functional beverage, and cosmetic applications, where consistent specification and documented sourcing are valued by formulators. Recent capacity and sourcing expansions in Ecuador and Viet Nam signal a deliberate effort to strengthen raw-material security and improve traceability across key producing regions. Alongside that, the introduction of high-concentration bioactive solutions for beverage applications shows a push to connect chlorogenic acid more directly with flavor-compatible functional formats. This dual approach, supply resilience paired with application-driven innovation, positions the company to serve buyers who want both reliability and product development support.
Applied Food Sciences has built a distinct positioning around branded green coffee bean extracts with defined chlorogenic acid content, particularly for dietary supplements, weight-management, and metabolic health formulations. This brand-and-specification strategy is well aligned with the demand-side shift toward clear functional claims and repeatable ingredient profiles. By emphasizing defined content and usage clarity, the company appeals to customers who need a recognizable ingredient identity for marketing and formulation purposes. In a market where generic botanical ingredients can be harder to differentiate, branded and specification-led offerings can create stronger customer loyalty and more defensible pricing.
EUROMED SA represents a pharmaceutical- and clinical-grade orientation, emphasizing high-purity botanical extracts for APIs, dietary supplements, and clinical-grade nutraceutical formulations. This positioning places the company closer to regulated and quality-intensive end uses, where documentation, purity, and process control carry greater weight. The strategic value of this approach lies in its alignment with higher-specification applications that often tolerate less price competition and more value on compliance and consistency. As the broader market expands into more demanding use cases, suppliers with credible high-purity capabilities may capture a disproportionate share of value relative to volume.
Sabinsa Corporation rounds out the competitive picture with a science-backed herbal and botanical API focus, including chlorogenic acid extracts supported by clinical validation. Its relevance lies in the intersection of pharmaceutical, nutraceutical, and preventive healthcare markets, where evidence and credibility are central to adoption. Companies operating in this space benefit when the market moves toward more substantiated claims and more rigorous buyer expectations, because clinical backing and scientific positioning become tangible differentiators rather than generic marketing language.
A notable feature of the competitive landscape is the presence of large-scale producers, particularly in China, that have built substantial export-oriented capacity for high-purity chlorogenic acid extracts. Some of these players have established meaningful global market shares and supply footprints across multiple countries. Their strength typically comes from scale, process efficiency, and the ability to serve a wide range of international buyers with defined purity grades. This creates a two-tier competitive dynamic: on one side, suppliers competing on volume, consistency, and price accessibility; on the other, companies competing on branding, clinical narrative, regulatory positioning, and application-specific value. The market is likely to continue supporting both tiers, but with increasing pressure on scale players to demonstrate more than cost leadership if they want to protect margins as the market matures.
The competitive evolution is also being shaped by a broader trend toward integration and specialization. Some suppliers are expanding upstream into sourcing hubs to reduce exposure and improve traceability. Others are developing application-focused product lines to capture more value in specific formats such as beverages or clinical nutraceuticals. At the same time, new entrants can still find opportunities if they bring a clearly defined niche, whether that is a particular purity standard, a specialized botanical source, or a targeted application competency. The most durable strategies appear to be those that combine operational reliability with a specific value proposition, rather than attempting to compete across every segment at once.
Forward Outlook: Three Trends to Watch
One likely trend over the next three to five years is the continued shift from generic chlorogenic acid supply to application-tailored solutions. As the ingredient becomes more familiar, buyers will increasingly expect support for specific formulation challenges, including stability, sensory compatibility, dosage clarity, and regulatory fit. Suppliers that invest in application development and provide practical formulation support are more likely to secure recurring demand and reduce vulnerability to price-based competition. The commercial opportunity here lies in creating defensible relationships with formulators and brands that value solutions over mere material supply.
A second trend is the growing importance of traceability, purity assurance, and documentation as baseline expectations rather than premium extras. This is being reinforced by both regulatory asymmetry and buyer behavior. As more companies sell into multiple markets, the ability to demonstrate consistent quality and clear sourcing becomes a commercial necessity. Suppliers that can standardize quality systems, provide reliable specification data, and maintain transparent sourcing pathways will be better positioned to serve international customers and reduce the friction associated with multi-market compliance. The upside is stronger customer trust and longer contract cycles; the risk is that any lapse in quality or documentation can spread quickly through a tightly connected buyer network.
A third trend is the potential for regional supply-chain reconfiguration as trade dynamics and sourcing economics evolve. Tariff adjustments, logistics costs, and production concentration all influence where and how chlorogenic acid inputs are sourced and processed. Over time, some suppliers may pursue more diversified sourcing strategies or regional processing arrangements to reduce exposure to any single origin or trade channel. For buyers, this could create both opportunities and risks: more sourcing flexibility can improve resilience, but frequent shifts in supply routes can also affect consistency and commercial terms. Companies that proactively monitor these shifts and build flexible sourcing strategies will be better prepared to manage cost and continuity.
Each of these trends carries embedded uncertainty. Regulatory frameworks may tighten in some markets or remain permissive in others, altering where the most attractive growth opportunities appear. Agricultural conditions could disrupt input availability and create pricing volatility that tests the resilience of weaker operators. And as the market expands, competitive intensity may increase in the most accessible segments, compressing the room for undifferentiated suppliers. The companies most likely to benefit will be those that treat these uncertainties as strategic variables to manage rather than external events to simply react to.
Strategic Actions for Decision-Makers
For ingredient manufacturers and suppliers, the priority is to strengthen the link between technical capability and commercial positioning. This means investing in consistent high-purity outputs, reliable traceability systems, and application-relevant support that helps buyers integrate chlorogenic acid more effectively into their products. Companies should also evaluate whether they are overly dependent on a single raw material pathway or a single geographic source, and consider whether portfolio diversification or upstream sourcing relationships can reduce vulnerability. In a market where scale alone is increasingly difficult to monetize, differentiation through quality assurance, formulation support, and application focus is likely to offer better long-term protection.
PW Consulting Health Care Research Center
For investors and strategic capital allocators, the relevant question is where value is likely to accumulate as the market matures. Volume growth is expected to continue, but the most attractive opportunities may lie in suppliers with credible differentiation in purity, clinical or scientific positioning, traceability, or application ownership. It is also worth distinguishing between businesses that depend primarily on commodity-style throughput and those that can capture more value through branded or specification-led offerings. Monitoring regulatory changes, trade policy shifts, and raw material concentration risk should be part of any investment thesis, because these factors can alter cost structures and market access faster than volume trends alone would suggest.
Ferulic Acid Market
For procurement and formulation teams, the practical focus should be on reducing exposure to inconsistency and compliance friction. This includes evaluating suppliers not only on price but also on specification reliability, documentation quality, and the ability to support multi-market requirements. Long-term supply agreements may be more valuable when paired with performance expectations around consistency and traceability. Procurement teams may also benefit from maintaining a diversified supplier base that includes both scale-oriented and specialty-oriented partners, allowing them to balance cost efficiency with resilience and application fit.
For all of these stakeholders, the strategic value of deeper intelligence is clear. The chlorogenic acid market is large enough to matter and dynamic enough to reward informed decisions, but its nuances, from regulatory asymmetry to raw material concentration and competitive differentiation, are difficult to navigate with high-level summaries alone. More detailed segmentation data, company-level positioning, and application-specific dynamics can materially improve sourcing, investment, and product development decisions. A comprehensive research report can provide that granularity, offering a more precise view of where demand is building, how competitive positions are evolving, and which supply and formulation strategies are most likely to withstand market volatility.
For detailed analysis of this topic, please visit the official page: Chlorogenic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Commercial Kitchen Ventilation Systems Market: Why 6.8% CAGR Signals Major Shifts
By PW Consulting, 2026-09-21
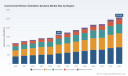
Commercial Kitchen Ventilation Systems Market: Strategic Trends and Commercial Opportunities Through 2032
The commercial kitchen ventilation systems market is entering a phase of structural transformation, driven by tightening environmental mandates, accelerating energy-efficiency expectations, and a fundamental shift in how foodservice operators approach kitchen infrastructure. Valued at approximately $1.63 billion in 2025, the market is projected to expand at a compound annual growth rate of 6.8 percent through 2032, crossing the $2.58 billion threshold by the end of the forecast period. The growth trajectory reflects more than incremental replacement demand; it signals a rebalancing of how commercial kitchens are designed, regulated, and optimized for operational cost and compliance performance.
Historical momentum has been steady rather than explosive, with annual revenue progressing from $1.15 billion in 2020 toward the mid-$1.6 billion range by 2025. The acceleration in the 2025-2032 window is rooted in a confluence of regulatory upgrades, retrofit activity in aging foodservice footprints, and manufacturer-level innovation that is converting ventilation from a passive exhaust utility into an active energy and air-quality management asset. For executives, planners, and capital allocators, the strategic question is no longer whether the market will grow, but which sub-segments, geographies, and competitive positions will capture disproportionate value as standards tighten and operating economics shift.
Navigating the Current Inflection Point
Three structural challenges are reshaping how commercial kitchen ventilation markets evolve and how players position themselves within them.
The first is the regulatory ratchet. Kitchen ventilation has historically been governed by a patchwork of fire-safety, mechanical, and food-code requirements. The current trajectory moves beyond containment toward active performance standards. Recent proposals from the California Energy Commission point toward code changes designed to improve energy efficiency and reduce greenhouse gas emissions in commercial kitchens, including the potential introduction of mandatory Demand Control Kitchen Ventilation (DCKV) requirements as the next progression beyond existing standards. When jurisdictional frameworks begin to tie ventilation performance to energy usage and emissions, the market shifts from discretionary spend to compliance-driven investment, which changes the sales cycle, specification logic, and competitive differentiation for manufacturers and service providers alike.
The second challenge is the growing gap between installed base reality and modern performance expectations. Many commercial kitchens continue to operate with legacy exhaust hoods, fixed-speed fans, and non-integrated air management systems that were specified under older mechanical codes and pre-efficiency cost assumptions. Retrofitting these environments requires more than equipment swaps; it demands airflow engineering, grease management coordination, fire suppression compatibility, and controls integration. This elevates project complexity and favors suppliers that can deliver engineered solutions rather than commodity components. It also raises the stakes for installers and service networks, since performance guarantees increasingly depend on proper commissioning and ongoing maintenance.
The third challenge is cost structure volatility interacting with energy economics. Electrical pricing, refrigeration loads, cooking equipment heat output, and building envelope performance all influence the total cost of ownership for kitchen ventilation. A system that performs adequately from a compliance standpoint may still impose avoidable energy expenditure if airflow is not modulated to actual cooking load. As operators face sustained pressure on margins, the economic case for smarter ventilation becomes more compelling, but it also demands clearer quantification of savings, more credible performance data, and integration with broader kitchen energy strategies. The market is therefore moving toward solutions that can demonstrate a measurable link between ventilation control and operating cost reduction.
Key Drivers Behind Market Expansion
Technology Innovation and Demand-Controlled Ventilation
The most consequential technology trend in commercial kitchen ventilation is the shift toward demand-controlled operation. Instead of running exhaust and makeup air at fixed capacities, DCKV systems adjust airflow based on real-time cooking activity, thermal load, or contaminant detection. This approach directly addresses the energy penalty of over-ventilation, which has long been an overlooked source of waste in commercial kitchens. By matching ventilation output to operational demand, facilities can reduce fan energy consumption, lower heating and cooling losses, and improve hood capture efficiency under variable cooking conditions.
This innovation is not occurring in isolation. It is converging with broader building controls, digital commissioning tools, and smarter air-flow management architectures. Providers such as Systemair and Melink illustrate the direction of travel with offerings that combine exhaust performance with smart flow controls and demand-controlled ventilation solutions, while companies with DCKV-focused portfolios such as Gaylord and Melink emphasize modulation as a core value proposition. The strategic implication is clear: ventilation hardware is increasingly evaluated not only by capture area, material durability, and fire-safety conformance, but also by how effectively it integrates with controls that minimize idle energy use.
Residential Ventilation Systems Market
Regulatory Pressure as a Market Accelerator
Regulation is becoming a primary catalyst for both new construction specifications and retrofit programs. The FDA Food Code requires commercial kitchen exhaust systems to capture and contain heat, smoke, grease, and vapors to protect public health, while NFPA 96 sets mandatory requirements for ventilation control and fire protection in commercial cooking operations. These frameworks establish the floor for safe ventilation design. The emerging layer is the energy and emissions dimension, where jurisdictions are exploring requirements that go beyond containment and address efficiency performance.
At the installation and mechanical design level, updated model codes such as the 2021 Uniform Mechanical Code provide the baseline requirements for safe installation of commercial kitchen ventilation and exhaust systems. As local jurisdictions adopt, modify, or layer additional performance expectations on top of these standards, the specification environment becomes more formalized and more consequential. For manufacturers, this creates a dual opportunity: compliance assurance remains a licensing requirement for market participation, but added-value solutions that help operators meet evolving efficiency expectations can command stronger positioning and more resilient demand.
Demand-Side Shifts in Foodservice Operations
The application landscape reflects a broad, diversified demand base rather than reliance on a single end-use channel. Restaurants and cafes continue to represent the largest application share, supported by ongoing build-out, refresh cycles, and the need to upgrade older ventilation installations. Hotels and hospitality facilities contribute a substantial secondary demand stream, where ventilation is tied not only to kitchen safety but also to guest-facing comfort, indoor air quality, and multi-use facility performance. Corporate and industrial canteens, educational institutes, and hospitals and healthcare facilities each bring distinct operating requirements and procurement cycles, broadening the market’s resilience and reducing dependence on any single sector’s investment timing.
Operationally, the demand story is being shaped by labor, throughput, and risk management considerations. Kitchens are under pressure to improve consistency, reduce downtime, and simplify maintenance. Ventilation systems that are easier to commission, cleaner to service, and better aligned with variable cooking loads can improve day-to-day reliability while reducing the operational burden on kitchen staff and facility teams. In institutional and healthcare settings, the air-quality and containment rationale is especially strong, reinforcing ventilation as part of broader facility safety and environmental control strategies.
Supply Chain and Cost Structure Dynamics
Cost structures in commercial kitchen ventilation are influenced by material inputs, fabrication complexity, ratings and certification requirements, and the labor associated with installation and service. For hoods and ducting assemblies, material selection, fabrication tolerances, and fire-rated components can materially affect both pricing and delivery timelines. For controls and makeup air systems, value is increasingly determined by integration capability, sensor reliability, and software-mediated performance optimization rather than by hardware alone.
This changing cost-and-value equation is nudging the market toward more bundled and engineered offers. Suppliers that can coordinate hood design, exhaust and supply airflow, grease management, fire suppression coordination, and controls into a coherent specification are better positioned to manage total project risk and capture more of the value chain. At the same time, component-level suppliers that can deliver certified, cost-competitive hardware with reliable lead times retain an important role, especially in retrofit and maintenance-driven demand. The competitive edge is moving toward coordination, specification support, and documented performance.
Competitive Landscape and Positioning Strategies
The market is characterized by a concentrated set of established manufacturers and a broader tier of regional and application-focused players. Concentration at the top reflects the importance of scale, certification depth, engineered product portfolios, and service reach in winning specification-driven projects. At the same time, fragmentation persists because commercial kitchen ventilation is not a single product category; it spans exhaust hoods, fans and ducting systems, makeup air units, controls and accessories, and installation services, with different competitors leading in different slices.
CaptiveAire Systems stands out as a broad-line manufacturer of commercial kitchen ventilation systems, including exhaust hoods, fans, grease management, and complete HVAC solutions for foodservice operations. Its positioning emphasizes a full-system capability that can address the integrated nature of modern kitchen design, where exhaust, makeup air, and grease handling must work together. Greenheck Fan Corporation similarly occupies a wide portfolio position, offering exhaust hoods, fans, make-up air units, and energy recovery ventilation for restaurants and foodservice. The strategic significance of this breadth is that it allows specification of complementary components under a more unified performance logic, which can reduce integration risk and simplify procurement for larger projects.
Systemair AB brings an advanced-exhaust and air-purification orientation, with high-performance air purifiers, smart air flow controls, and demand-controlled ventilation solutions. This places the company closer to the efficiency and controls frontier, where value is created through modulation, filtration, and system intelligence rather than through hardware volume alone. Gaylord Industries focuses on Demand Control Kitchen Ventilation systems, custom kitchen hoods, and pollution control equipment for commercial foodservice, reinforcing a differentiated stance around active ventilation control and custom engineering. FAST Kitchen Hoods contributes a more specialized, regionally anchored presence as a Canadian manufacturer of cULus-rated commercial kitchen hoods, exhaust systems, island hoods, and low-ceiling hoods for restaurants, illustrating how rating compliance and form-factor specialization can anchor a defensible niche.
Chef’s Deal Restaurant Equipment operates with a service-intensive model as a supplier and installer of comprehensive commercial kitchen ventilation systems, including engineered hoods, make-up air units, ventless exhaust, Type 1 and Type 2 grease hoods, and related accessories. Its recent expansion of its Commercial Kitchen Hood Service portfolio to include fully engineered ventilation systems, professional consultation, customized hood packages, make-up air units, ventless exhaust, Type 1 grease hoods, Type 2 condensate hoods, food truck hoods, pizza oven hoods, fire suppression, and exhaust hood filters and accessories for restaurants, food trucks, retailers, and institutional kitchens reflects a deliberate move toward broader solution coverage and consultative specification support. North American Kitchen Solutions maintains a multi-site U.S. footprint with manufacturing of commercial kitchen hoods, exhaust and supply fans, fire suppression, and portable ventless hood systems, showing how geographic and product diversification can support both project-based and supply-driven demand.
How Leaders Differentiate
Across these players, differentiation tends to cluster around several strategic levers. The first is portfolio breadth versus specialization. Full-line providers compete on integration, specification ease, and project-scale capability. Specialists compete on performance depth, rating expertise, or application fit. The second lever is controls and efficiency capability. As energy and emissions expectations rise, manufacturers that can demonstrate meaningful demand-controlled operation, reliable airflow modulation, and credible energy outcomes are better positioned for specification advantage. The third lever is installation and service reach. Ventilation performance depends heavily on proper sizing, duct routing, commissioning, and ongoing maintenance, so providers with strong field capacity can convert product capability into realized performance. The fourth lever is compliance and ratings fluency. In a market shaped by mechanical codes, fire-safety standards, and food-code requirements, the ability to navigate certification and demonstrate conformance is a basic but essential competitive precondition.
Market Structure Evolution
The competitive structure is likely to evolve along three lines. First, integration pressure will increase as operators and specifiers seek fewer interfaces between hood, fan, makeup air, controls, and suppression. This favors companies that can deliver coordinated designs and may encourage selective partnerships or acquisitions that close capability gaps. Second, the controls and efficiency layer will become more valuable, creating openings for players that can bring software-mediated ventilation management, better sensor integration, and verifiable savings narratives into the market. Third, regional and application-focused specialists will continue to find room to compete, especially where local code interpretation, rating requirements, or niche form factors such as low-ceiling or mobile-food applications create specificity that larger portfolios do not automatically address.
Future Trends and Commercial Opportunities
Efficiency Mandates Will Move From Optional to Expected
The most consequential near-to-medium-term trend is the normalization of demand-controlled and efficiency-oriented ventilation as a standard expectation rather than a premium option. With regulatory discussions increasingly pointing toward mandatory DCKV-style requirements in leading jurisdictions, and with model codes and food-safety standards already establishing the containment baseline, the market is heading toward a two-layer framework: safe capture and fire protection as the foundation, and active efficiency performance as the differentiating expectation. Commercial opportunity lies in products and services that can make demand-controlled operation reliable, easy to commission, and simple to verify after installation. Manufacturers and integrators that can reduce the friction of controls adoption—through clearer specification tools, more robust sensor performance, and stronger field support—will be well placed to convert regulatory momentum into specification share.
Retrofit and Performance Upgrades Will Outpace Pure New-Construction Demand
Given the size and age of existing foodservice footprints, a significant portion of future demand will come from upgrading or replacing ventilation systems that no longer meet current performance, safety, or efficiency expectations. Retrofit demand is more fragmented and more service-intensive than new construction, but it also creates opportunities for engineered assessments, phased replacement programs, and controls retrofits that improve energy performance without full kitchen rebuilds. The commercial opportunity here is in bundled upgrade packages that pair hood or fan replacement with airflow rebalancing, controls integration, and grease management review. Providers that can quantify pre- and post-upgrade performance and reduce operational disruption will have an advantage in this segment.
PW Consulting Automotive & Machinery Research Center
Smart Air Management and Integrated Kitchen Energy Design Will Gain Share
Ventilation is increasingly being evaluated as part of the broader kitchen energy and air-quality system rather than as a standalone exhaust function. This creates a trend toward tighter integration between exhaust, makeup air, temperature control, and demand modulation, with controls acting as the connective tissue. The opportunity is for suppliers that can position kitchen ventilation as an energy-management asset with measurable impact on fan power, thermal load, and indoor comfort. It also opens the door to more sophisticated service models, including performance monitoring, scheduled commissioning checks, and data-informed maintenance. As operators look for ways to manage operating costs and meet internal sustainability expectations, integrated air management solutions will become more relevant and more defensible.
Risks and Uncertainties
The outlook carries meaningful uncertainty. Code adoption is uneven across jurisdictions, so the pace and shape of mandatory efficiency requirements will vary, creating a patchwork rather than a uniform transition. Economic conditions can shift the timing of restaurant build-outs, hospitality renovations, and institutional procurement cycles, affecting demand volatility. Supply chain and input cost pressures can influence hardware pricing and project economics, particularly for fabrication-intensive components. Finally, the promised energy and operational savings from controls-based ventilation depend on correct design, installation, and ongoing calibration; if realized performance falls short of expectations, trust in efficiency narratives can erode. Participants should therefore treat performance validation, service quality, and transparent specification as strategic necessities rather than supporting functions.
Actionable Recommendations for Decision-Makers
For Manufacturers and Solution Providers
Position around integration, not just equipment. The market is rewarding providers that can coordinate hood design, airflow balance, controls, grease management, and fire protection into a coherent offer. Invest in specification support, commissioning expertise, and post-installation performance validation so that efficiency claims are credible and repeatable. Where portfolio breadth is not achievable, build clear differentiation around a specialized strength such as demand-controlled control logic, rating compliance for a specific form factor, or a service model that reduces install and maintenance friction. Monitor regulatory signals closely, especially jurisdictional moves toward efficiency-oriented kitchen ventilation requirements, and prepare specification tools and product configurations that align with the next code progression.
Worldwide Commercial Kitchen Fire Suppression System Market
For Investors and Capital Allocators
Evaluate exposure to the efficiency and controls layer as a distinct value driver. Pure hardware volume plays may continue to perform, but the higher-margin, higher-differentiation opportunity is increasingly tied to demand-controlled ventilation, integration services, and performance verification. Consider the mix of new-construction exposure versus retrofit and service exposure in any target, since retrofit-heavy models can be more resilient to construction-cycle volatility while demanding stronger field and service capabilities. Assess regulatory sensitivity as part of the investment thesis: companies aligned with the direction of tightening efficiency expectations are better positioned than those dependent on discretionary, low-performance specifications. In due diligence, probe installation quality, commissioning processes, and the evidence base for energy or operating-cost claims, because these factors increasingly determine whether a product wins repeat specification.
For Procurement and Facility Decision-Makers
Treat kitchen ventilation as a total-cost and compliance asset, not merely a capex line item. Specify with attention to demand-controlled capability, proper airflow design, grease management integration, and fire-safety conformance, and require clear commissioning and performance verification before project closeout. Evaluate suppliers on their ability to deliver engineered solutions and documented post-installation performance, not only on unit pricing. Where existing systems are underperforming, consider targeted retrofits that improve modulation and control before committing to full replacements, and align ventilation decisions with broader kitchen energy and maintenance strategies to capture operational savings over time.
The commercial kitchen ventilation market is moving from a compliance-and-commodity orientation toward a performance-and-integration orientation. That shift creates winners among companies that can combine certification strength, engineering depth, controls capability, and service reliability, while leaving narrower or purely transactional models exposed to margin and specification pressure. As efficiency expectations mature and retrofit demand expands, the strategic value of timely, granular market intelligence becomes harder to overstate. Decision-makers who understand where regulation is heading, how controls are reshaping operating economics, and which competitive positions are gaining specification advantage will be better equipped to allocate capital, prioritize product roadmaps, and structure procurement around the next phase of market growth.
For detailed analysis of this topic, please visit the official page: Commercial Kitchen Ventilation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Isoparaffin Solvents Market: Why 3.5% CAGR and $1.14B Trajectory Mask Hidden Shifts
By PW Consulting, 2026-09-21
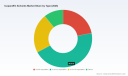
Isoparaffin Solvents Market: Navigating the Strategic Crossroads of Sustainability, Compliance, and Growth
The isoparaffin solvents market has entered a phase of measured maturation, shaped by tightening environmental mandates, evolving application demands, and a competitive landscape that rewards precision and compliance. After reaching a valuation of approximately 905.16 million USD in 2025, the sector is projected to expand at a compound annual growth rate of 3.5 percent through 2032, culminating in a market size near 1,144.78 million USD. This trajectory reflects more than steady demand growth; it signals a structural shift in how formulators, manufacturers, and regulators evaluate solvent performance, safety, and sustainability.
While the broader market moves forward on a moderate growth curve, the underlying dynamics are anything but uniform. Revenue distribution across regions and applications reveals a market that is geographically diversified but application-concentrated, with heavy reliance on industrial and specialty formulations that demand high-purity, low-odor hydrocarbon solvents. The competitive field remains moderately fragmented, with the top three players capturing roughly 28.3 percent of market share and the top five holding about 32.1 percent. Such concentration suggests that scale, technical differentiation, and regional capacity positioning matter significantly, yet they also leave space for niche players and innovative entrants to compete on performance, compliance, and supply reliability.
As 2025 transitions into the forecast period, the isoparaffin solvents market is being reshaped by environmental compliance, feedstock economics, and application-specific performance requirements. These forces are not isolated; they intersect to create both constraints and openings for companies that can align product portfolios with emerging regulatory and operational realities.
Market Landscape: Performance, Pressure Points, and the 2026-2032 Trajectory
A Market Defined by Steady Expansion and Structural Complexity
The isoparaffin solvents market has demonstrated consistent expansion across the 2020-2025 period, supported by enduring demand in paints and coatings, metalworking fluids, agrochemicals, cleaning formulations, pharmaceuticals, and personal care. This breadth of use underscores the versatility of isoparaffinic hydrocarbons as low-aromatic, low-odor alternatives to traditional solvent systems. However, breadth does not imply uniformity. Demand patterns vary by end-use performance requirements, regional manufacturing footprints, and regulatory exposure, creating a market where growth is unevenly distributed across segments and geographies.
Forecasting through 2032 suggests continued expansion, but also highlights a market that must balance volume growth with margin discipline. Feedstock-linked cost volatility and regulatory compliance costs place pressure on producer economics, while downstream customers increasingly prioritize product consistency, purity, and documentation. In this environment, market growth is less a simple function of demand volume and more a result of value capture through differentiated grades, technical support, and supply reliability.
Critical Challenges and Inflection Points
Several structural challenges are reshaping the competitive and operational landscape for isoparaffin solvent producers and users.
- Feedstock volatility and margin sensitivity: The production economics of isoparaffin solvents are closely tied to hydrocarbon feedstock dynamics. Price swings, availability constraints, and energy cost fluctuations can compress margins and complicate long-term pricing strategies. This sensitivity forces producers to manage cost structures carefully while maintaining product quality that meets stringent application specifications.
- Regulatory tightening on VOCs and aromatic content: Environmental regulation continues to redefine the acceptable boundary for solvent use. In multiple regions, including parts of South America, restrictions on volatile organic compound emissions and aromatic content have become more rigorous, especially for paints, coatings, and adhesives. These rules accelerate the shift toward high-purity isoparaffin grades but also increase compliance burdens and formulation complexity for downstream users.
- Performance versus sustainability trade-offs: Downstream formulators face a dual mandate. They need solvents that deliver consistent dissolution, evaporation, and rheological behavior, while also meeting sustainability goals and regulatory limits. Balancing performance, odor, toxicity perception, and carbon footprint is becoming a core product selection criterion rather than a secondary consideration.
These challenges are not merely obstacles. They are inflection points that reward players with strong technical portfolios, dependable supply, and clear regulatory alignment. Companies unable to navigate these pressures risk margin erosion, substitution risk, or loss of share in applications where compliance is a prerequisite.
Key Drivers Reshaping the Isoparaffin Solvents Market
Regulatory and Environmental Mandates as a Growth Accelerator
Environmental regulation is one of the most influential forces behind current market dynamics. In the United States, EPA VOC limits and in Europe, the Solvent Emissions Directive continue to steer formulators away from higher-aromatic solvent systems toward high-purity, low-aromatic alternatives. Isoparaffin solvents, with their low odor and reduced aromatic content, are increasingly positioned as compliant substitutes in applications where emissions limits and workplace safety requirements are tightening.
This regulatory pressure is particularly visible in regions where paint, coating, and adhesive manufacturers must meet stricter emission thresholds. In South America, for example, countries such as Brazil and Argentina have moved to tighten VOC emission standards between 2023 and 2025, mandating reduced aromatic content in solvents used across paints, coatings, and adhesives. Such measures do not simply constrain the market; they redirect it. Demand flows toward solvent grades that can satisfy compliance requirements without sacrificing application performance, and isoparaffins are well placed to benefit from that redirection.
Product Innovation Centered on Purity, Odor, and Application Fit
Technological progress in isoparaffin solvents is increasingly focused on refining product attributes rather than simply expanding volume. Leading suppliers are updating technical documentation, emphasizing low odor, low aromatic content, and narrow boiling ranges, and aligning products with specific formulation needs in coatings, cleaning, metalworking, and personal care. This is not cosmetic repositioning; it reflects a real shift in market expectations. Formulators want solvents that reduce odor complaints, improve workplace conditions, and enable cleaner formulations while preserving solvency performance.
Recent product and documentation updates from major players illustrate this direction. ExxonMobil Chemical updated the technical datasheet for Isopar M, highlighting low aromatic content. Shell Chemicals released an updated product datasheet for ShellSol, emphasizing low odor and suitability for surface coatings. These actions signal that competitive advantage is increasingly linked to grade-level differentiation and technical clarity, not just brand recognition. When downstream customers compare solvent options, the ability to demonstrate purity, consistency, and application-specific fit can be decisive.
Demand-Side Shifts in Coatings, Metalworking, and Specialty Formulations
Demand for isoparaffin solvents is being reshaped by changing expectations in major application categories. Paints and coatings remain a central use case, but the drivers within this segment are evolving. Coatings formulators are under pressure to reduce VOC emissions, improve indoor air quality, and support sustainability claims. Metalworking fluids and industrial cleaning applications continue to value low-odor, effective hydrocarbon solvents that support degreasing, parts cleaning, and process consistency. Agrochemical formulations also contribute to demand, where solvent choice can influence product stability, handling, and regulatory acceptability.
At the same time, personal care and pharmaceutical applications, while smaller in absolute terms, represent high-value segments where purity, odor control, and regulatory documentation matter disproportionately. In these markets, even modest volume growth can be strategically meaningful because the margin and differentiation potential is higher. The broader implication is that demand growth is not only a volume story; it is increasingly a value story, with certain applications generating stronger pull for premium, high-purity grades.
Capacity Adjustments and Regional Supply Positioning
Supply-side dynamics are also influencing market direction. Recent capacity actions by major producers point to a focus on regional availability and application-oriented supply reliability. In February 2025, Shell Chemicals inaugurated a new isoparaffin solvent production plant in Brazil, increasing local capacity by 30 percent. In March 2025, Chevron Phillips Chemical increased its manufacturing capacity for isoparaffin solvents. These developments matter because regional production can shorten supply chains, reduce logistical risk, and better serve local regulatory and application requirements.
For buyers, the practical implication is greater importance placed on supply continuity and regional support. For producers, the lesson is that capacity deployment is most effective when aligned with local demand intensity, compliance conditions, and distribution capabilities. As capacity expands in key regions, competition may intensify on service level, formulation support, and availability rather than price alone.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
How Leading Players Are Shaping the Field
The competitive landscape in isoparaffin solvents is shaped by large chemical and energy-linked companies with broad hydrocarbon portfolios and strong technical reputations. These players compete not only on scale, but on product clarity, application support, and regulatory alignment. Several firms stand out for distinct positioning.
Solvent Naphtha Market
- Shell Chemicals has built a strong identity around ShellSol isoparaffins, emphasizing high-purity synthetic hydrocarbon solvents with narrow boiling ranges and low impurities. The brand is associated with coatings, inks, dry cleaning, and industrial applications, and recent updates have reinforced low-odor performance and surface coating suitability. Its February 2025 plant inauguration in Brazil also demonstrates a strategy of strengthening regional supply and local capacity.
- Chevron Phillips Chemical Company is recognized for Soltrol isoparaffin solvents, including Soltrol 130, which are positioned as low-odor and compatible with parts cleaning, degreasing, paints, inks, and agrochemical formulations. The March 2025 capacity increase signals continued investment in meeting demand for versatile, compliant solvent grades.
- ExxonMobil Chemical markets Isopar fluids with a focus on high purity, low aromatic content, and odorless properties for personal care, coatings, cleaning, and metalworking. The July 2025 technical datasheet update for Isopar M underscores a strategy of reinforcing product differentiation through documented purity and application-specific attributes.
- Braskem S.A. and TotalEnergies SE both participate in the market through broader hydrocarbon and chemical portfolios, supplying isoparaffin solvents for industrial and specialty applications, including paints and coatings. Their relevance lies in portfolio breadth and the ability to integrate solvent offerings within larger supply relationships.
- INEOS Group, Idemitsu Kosan, Calumet Specialty Products Partners, Sasol Limited, and SK Global Chemical each bring regional or specialized strengths. INEOS focuses on industrial cleaning, coatings, and personal care; Idemitsu Kosan supplies IP Clean and IP Solvent products; Calumet emphasizes industrial cleaning and coatings; Sasol participates through its chemical portfolio; and SK Global Chemical offers ISOL isoparaffins for industrial solvents and formulations.
What connects these players is a shared recognition that isoparaffin solvents are no longer commoditized cleaning or dissolving agents alone. They are increasingly evaluated as engineered chemical inputs with specific performance, safety, and compliance profiles. In this context, technical documentation, application expertise, and consistent quality become central competitive tools.
Strategic Positioning and Differentiation Levers
Leading companies are pursuing differentiation through several interlocking levers.
De-Aromatic Solvents Market
- Purity and low-aromatic positioning: In markets where VOC limits and aromatic content restrictions are tightening, high-purity grades gain an advantage. Suppliers that can clearly document low aromatic content and odor performance strengthen their relevance for compliant formulations.
- Application-focused product architecture: Rather than offering a single generic solvent, successful players tailor grades to specific uses such as coatings, metalworking, cleaning, personal care, and agrochemicals. This application alignment improves customer fit and reduces substitution risk.
- Regional capacity and supply visibility: Local production and reliable logistics reduce vulnerability to freight volatility and can improve responsiveness to regional regulatory changes. Brazil’s capacity expansion and broader capacity increases elsewhere illustrate the strategic value of placing supply closer to demand.
- Technical communication and datasheet clarity: Updated datasheets and product documentation are not administrative tasks; they are market-facing signals. Clear specifications help formulators validate compliance, compare alternatives, and justify solvent selection to internal and external stakeholders.
Together, these levers create a competitive environment where advantage is built through reliability, specificity, and compliance readiness rather than through broad volume claims alone.
Market Evolution: Consolidation, Fragmentation, and Entrant Dynamics
The market’s moderate concentration suggests room for both consolidation and targeted fragmentation. On one hand, large integrated players benefit from scale, feedstock access, and portfolio breadth, which can support pricing resilience and global reach. On the other hand, the presence of multiple capable regional and specialty suppliers means that differentiation by region, application, and grade remains viable.
Over the next several years, the landscape may evolve along three directions. First, selective consolidation could occur as players seek to strengthen geographic coverage, product ranges, or application expertise. Second, fragmentation may persist or deepen in high-value specialty niches where purity, odor, and documentation command premiums. Third, new entrants or expanding regional producers may gain ground by addressing local compliance needs and supply reliability more nimbly than global incumbents. The outcome will depend on how well companies align capacity, product grades, technical support, and regulatory preparedness with regional demand patterns.
Future Outlook: Three Trends Shaping the 2026-2032 Window
Trend 1: Compliance-Driven Grade Migration Toward High-Purity Isoparaffins
As VOC limits and aromatic content rules continue to tighten across multiple regions, a clear trend is the migration toward high-purity isoparaffin grades that can satisfy regulatory requirements while maintaining formulation performance. This shift is not just a regulatory response; it is becoming a procurement and product development preference. Formulators are increasingly choosing solvents that reduce compliance risk, lower odor concerns, and support sustainability narratives.
The commercial implication is that demand may grow more strongly for specific premium grades than for the market as a whole. Producers and buyers alike should expect a bifurcation in which high-purity, well-documented products capture disproportionate value, while undifferentiated grades face greater substitution pressure. The opportunity lies in aligning product portfolios with the grades that regulatory and performance trends are pulling toward.
Trend 2: Regional Supply Diversification and Near-Market Capacity
Another likely trend is continued regional diversification of supply. Recent capacity expansions in South America and capacity increases elsewhere suggest that producers are looking to reduce exposure to long supply chains and better serve local demand and compliance conditions. Over the forecast period, regional availability may become a more important purchase criterion, especially in markets where logistics cost, lead time, and regulatory context vary significantly.
For buyers, this trend creates opportunities to diversify supply sources and reduce dependency on a single route. For producers, it emphasizes the value of localized capacity, distribution partnerships, and application support that match regional market conditions. The risk is that overexpansion in one region could create localized oversupply, while underinvestment in another could leave demand underserved and open the door to imports or competitor entry.
Trend 3: Application-Specific Value Creation in Coatings, Cleaning, and Specialty Use
A third trend is the growing importance of application-specific value creation. Paints and coatings will remain a dominant demand pool, but the most strategic growth may come from tailored solutions that address odor, purity, and regulatory documentation in coatings, metalworking fluids, cleaning, and specialty formulations such as personal care and pharmaceuticals. These segments reward precision, consistency, and technical support, and they can generate stronger margins than bulk-oriented applications.
This trend opens opportunities for suppliers that can provide not just solvent volume, but formulation guidance, compliance documentation, and grade optimization. It also creates risk for players that compete primarily on price without offering the technical assurance that formulators increasingly require. In practice, the market is likely to reward those who treat isoparaffins as part of a broader solution rather than as a standalone commodity.
Strategic Implications and Action Guidance for Decision Makers
For Manufacturers and Producers
Producers should prioritize grade-level differentiation and regulatory readiness. As compliance becomes a stronger purchase driver, the ability to provide high-purity, low-aromatic, low-odor solvents with clear documentation will matter more than broad product claims. Capacity investments should be evaluated not only for volume potential but also for regional fit, feedstock exposure, and the ability to serve compliance-sensitive applications. Technical communication, including updated datasheets and application guidance, should be treated as a competitive asset that helps customers justify solvent selection and reduce formulation risk.
For Investors and Financial Stakeholders
Investors should look beyond aggregate market growth and focus on where value is concentrating. Segments and grades tied to regulatory compliance, odor reduction, and high-purity requirements are more likely to deliver durable demand and margin resilience than undifferentiated bulk solvent exposure. Regional supply dynamics also matter: capacity expansions and local production can strengthen competitive positioning, but they also create execution risk if demand growth is uneven. A careful assessment of feedstock exposure, regulatory alignment, and application mix is essential when evaluating companies in this space.
For Procurement and Formulation Teams
Procurement and formulation decision-makers should treat isoparaffin selection as a strategic variable rather than a tactical purchase. Compliance documentation, aromatic content, odor profile, and supply reliability should be weighted alongside price. Because regulatory requirements and application performance needs differ by region and formulation, it is wise to validate supplier capability across the specific grades and use cases that matter most. Diversifying supply sources and seeking suppliers with strong regional presence can reduce vulnerability to logistics disruptions and regulatory shifts.
Why Timely, Granular Intelligence Matters
The isoparaffin solvents market is moving through a period in which aggregate growth numbers tell only part of the story. Regulatory pressure, grade-level differentiation, regional capacity shifts, and application-specific demand are creating a landscape where timing, specificity, and supply positioning determine outcomes. For companies making investment, production, or procurement decisions, access to detailed segmentation data, regional breakdowns, and company-level movement tracking can materially improve decision quality. Broad directional awareness is useful, but the real advantage lies in understanding which grades, regions, and applications are gaining or losing traction, and how competitors are adjusting capacity and product positioning in response.
For organizations that need deeper coverage of market size by segment, regional demand patterns, competitive activity, and customized strategic recommendations, a comprehensive market research report can provide the structured detail required to move from general insight to concrete action. Detailed data, scenario-ready segmentation, and forward-looking assessment are particularly valuable when planning capacity, evaluating suppliers, or positioning product portfolios for compliance-led demand shifts.
Conclusion
The isoparaffin solvents market is not experiencing a sudden disruption; it is undergoing a deliberate restructuring shaped by environmental compliance, product purity expectations, regional supply strategy, and application-specific performance needs. The forecast growth path through 2032 suggests a market that continues to expand, but the more important story is where value is being created and where competitive advantage is being built. High-purity, low-odor, compliance-aligned grades are gaining relevance, regional capacity is becoming a strategic differentiator, and technical clarity is increasingly part of the commercial battleground.
PW Consulting Automotive & Machinery Research Center
For executives, investors, and procurement leaders, the practical question is no longer whether isoparaffin solvents remain important, but how to position for the next phase of demand migration, regulatory pressure, and supplier competition. Companies that align their strategies with these trends, and that invest in the intelligence needed to track them closely, are better placed to capture value in a market where growth and differentiation are increasingly inseparable.
For detailed analysis of this topic, please visit the official page: Isoparaffin Solvents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PRP Market Analysis: How 10.5% CAGR to $1B Reshapes Orthopedics and Aesthetics
By PW Consulting, 2026-09-21
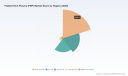
The Platelet-Rich Plasma Market: Strategic Trends and Commercial Opportunities in Autologous Biologics
The global platelet-rich plasma (PRP) market has evolved from a niche regenerative modality into a structured commercial ecosystem, driven by clinical adoption across orthopedics, sports medicine, aesthetics, and wound care. With historical revenue expanding from approximately $236.5 million in 2020 to $512.0 million in 2025, and a projected trajectory toward $1,032.3 million by 2032, the sector reflects a compound annual growth rate of 10.5 percent. This growth is neither uniform nor accidental. It emerges from a convergence of technological maturation, shifting reimbursement pathways, regulatory clarification, and demand-side preferences that favor autologous, minimally processed biologics. For executives, investors, and procurement leaders, the current moment represents a transition from early experimentation to scaled commercialization. The challenge lies in navigating a fragmented supply base, inconsistent coverage models, and evolving clinical evidence while capturing value in segments where efficacy, workflow integration, and reimbursement alignment intersect.
The market structure reveals a moderately concentrated landscape, with the top three players accounting for roughly 47.2 percent of revenue and the top five reaching 52.8 percent. This concentration suggests that scale, regulatory clearance, and system integration confer meaningful advantages, yet substantial runway remains for differentiated technologies and regional expansion. Growth is not evenly distributed across applications or geographies. Orthopedic and sports medicine use cases continue to anchor demand, while aesthetic and wound care applications present distinct reimbursement and clinical-evidence dynamics. The following analysis examines the forces shaping this transition, the strategic postures of leading participants, and the practical implications for decision-makers seeking to capitalize on the next phase of market development.
Plasma Protein Therapeutics Market
Market Snapshot: Growth Trajectory and Structural Realities
Over the 2020–2025 period, the PRP market expanded at a pace that outpaced many adjacent medical device and biologics segments. Revenue climbed from $236.5 million to $512.0 million, and forward projections indicate continued expansion through 2032, with annual figures moving from $579.7 million in 2026 to $1,032.3 million in 2032. This trajectory implies a sustained 10.5 percent CAGR, reflecting both underlying volume growth and incremental adoption of point-of-care preparation systems. The market’s composition spans multiple product formats, including pure PRP, leukocyte-rich variants, platelet-rich fibrin, and ancillary systems, alongside application breadth that covers orthopedic reconstruction, sports injury management, cosmetic procedures, and chronic wound care.
Despite the favorable headline numbers, the market operates within a set of structural constraints that shape commercial strategy. First, clinical evidence remains uneven across indications, with stronger data in select musculoskeletal and wound applications and more limited consensus in aesthetic and certain orthopedic injection contexts. Second, reimbursement pathways are partial and indication-specific, creating adoption friction in settings where providers cannot reliably pass through preparation costs. Third, regulatory classification creates a dual-track environment: FDA-cleared preparation devices enable compliant autologous use, while off-label applications depend on provider discretion and often lack broad coverage. Together, these realities mean that market growth is increasingly tied to workflow efficiency, evidence generation, and reimbursement alignment rather than to scientific novelty alone.
Key Challenges and Inflection Points
The PRP sector stands at several inflection points that will determine which participants capture durable value. One central challenge is the evidence-to-reimbursement gap. While point-of-care systems have improved consistency and reduced preparation variability, payers and institutions increasingly require indication-specific data, standardized protocols, and transparent cost accounting. Without these, adoption remains concentrated in cash-pay, sports medicine, and high-income aesthetic segments, limiting broader institutional uptake.
A second challenge involves cost structure and sterilization logistics. Single-use processing components, hemapheresis kits, and point-of-care consumables depend on gamma sterilization and small-batch manufacturing, which elevate unit costs and constrain margin flexibility. Suppliers must balance clinical-grade reliability with economic scalability, particularly as volume expectations rise and hospital procurement teams normalize total-cost-of-ownership assessments.
A third inflection point is regulatory clarity versus clinical flexibility. Autologous PRP devices are classified as Class II under 21 CFR 864.9245 and require 510(k) clearance, while PRP itself is regulated as a blood product by FDA CBER and is generally considered investigational for most non-wound applications. This framework ensures compliance for cleared autologous use but leaves many orthopedic and aesthetic injections in a provider-discretion zone without broad insurance coverage. The result is a market where device clearance, coding specificity, and clinical protocol design are increasingly intertwined commercial variables rather than purely regulatory checkboxes.
Core Drivers of Market Change
Technology Innovation and Workflow Integration
The most consequential technological shift is the move toward point-of-care systems that combine high platelet yields, customizable formulations, and rapid preparation workflows. Automated separation platforms, double-syringe kits, and single-spin systems have reduced preparation time and improved reproducibility, making PRP more viable in busy clinical environments. Systems that enable up to 18x platelet concentration at the point of care, or that deliver supraphysiologic concentrating with customizable formulations, address two practical barriers: clinical consistency and operational throughput. These capabilities matter because adoption in orthopedics and sports medicine often hinges on whether preparation can be embedded into existing procedure workflows without disrupting scheduling or staffing.
Technology differentiation is also moving toward application-specific optimization. In wound care, fibrin-based matrices and gel preparations that support exuding cutaneous wounds represent a distinct value proposition from injection-focused systems used in musculoskeletal settings. This specialization is creating a broader ecosystem in which device architecture, kit composition, and preparation protocol are increasingly matched to clinical use cases rather than sold as generic autologous blood products.
Policy and Regulatory Environment
Regulatory and coding developments are reshaping commercial viability. FDA clearance of PRP preparation systems establishes a compliance pathway for autologous use, while the broader classification of PRP as a blood product under FDA CBER keeps many non-wound applications in an investigational category. This duality means that device-level clearance does not automatically translate into coverage for every indication. Instead, commercial success increasingly depends on aligning cleared indications with coding structures and payer policies.
Worldwide Platelet Rich Plasma (PRP) Kit Market
Reimbursement dynamics are evolving in parallel. For chronic non-healing diabetic wounds, Medicare covers autologous PRP prepared with FDA-cleared devices under HCPCS G0465, with required invoice documentation for the PRP supply kit and an in-house processing fee. This creates a structured, if narrow, coverage pathway that rewards cleared devices and documented supply chains. At the same time, Category III coding such as 0232T applies to PRP injections across sites, including image guidance, harvesting, and preparation, with some payers requiring separate billing for supplies. These coding nuances affect provider economics and influence which systems are preferred in outpatient and institutional settings.
Demand-Side Shifts in Provider and Consumer Behavior
Demand is being reshaped by a preference for autologous biologics that minimize immunogenicity concerns and align with regenerative care models. In sports medicine and orthopedics, providers seek options that can be deployed during same-session procedures, reducing reliance on off-site processing and supporting rapid turnaround. In aesthetics, consumer interest in minimally invasive rejuvenation continues to drive volume, though this segment remains more sensitive to evidence messaging, pricing transparency, and outcomes consistency. In wound care, the demand driver is clinical necessity: chronic ulcers and non-healing wounds create a persistent care burden, and autologous PRP-based matrices offer a biologically aligned adjunct where standard dressings and therapies may be insufficient.
Across these settings, the common thread is a growing expectation that PRP should be reproducible, documented, and economically legible. Providers and procurement teams increasingly evaluate systems not only on platelet concentration claims but also on sterility assurance, kit reliability, ease of use, and compatibility with existing billing and documentation workflows.
Supply Chain and Cost Structure Evolution
Supply chain economics are becoming a strategic variable. Gamma sterilization requirements and small-batch manufacturing for single-use kits raise input costs, which can compress margins for manufacturers and increase total cost for providers. This environment favors participants that can standardize kit architectures, secure reliable sterilization pathways, and design systems that minimize waste or redundant consumables. It also rewards vertical alignment between device platforms and consumable supply, since fragmentation can introduce variability in both cost and clinical performance.
At the same time, distribution partnerships are altering market access. Agreements that place PRP systems under established brand channels can accelerate reach in specific clinical segments, particularly where wound care or orthopedic procurement is consolidated. Such arrangements can reduce the commercial burden on smaller manufacturers while expanding the availability of cleared systems within trusted distribution networks.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Participants
The competitive set reflects a mix of device-focused manufacturers, biologics integrators, and specialty developers pursuing differentiated preparation architectures. Several participants have built their positioning around point-of-care concentration performance and workflow reliability. EmCyte Corporation emphasizes a supraphysiologic concentrating system for point-of-care autologous PRP preparation with customizable formulations and high platelet yields, appealing to settings that value concentration control and formulation flexibility. Arthrex, Inc. focuses on an automated PRP system and double-syringe kits designed for orthopedic applications, enabling high platelet concentration at the point of care and integrating preparation into procedure workflows. Zimmer Biomet emphasizes integrated PRP systems and biologics kits that support orthopedic reconstruction and soft-tissue procedures, leveraging the advantages of an established orthopedic portfolio. Terumo BCT targets point-of-care PRP systems and related kits for rapid autologous preparation, with an emphasis on workflow speed and clinical usability.
PW Consulting
In parallel, several developers have pursued application-specific differentiation. Regen Lab S.A. focuses on PRP kits and systems optimized for clinical use in regenerative medicine applications, aligning product design with practitioner workflows. Royal Biologics has concentrated on fibrin-based PRP and PRF systems for wound management and bone graft handling, including a PRF wound matrix that recently received FDA clearance for management of exuding cutaneous wounds, including diabetic and venous ulcers. Nuo Therapeutics, Inc. has built a wound care and biodynamic therapy focus, with its PRP system distributed through private-label arrangements to Smith+Nephew in the U.S. wound care market. Gale Force Aesthetics, LLC emphasizes a single-spin system designed for high-volume platelet capture and rapid preparation, while Forever Labs, Inc. focuses on an automated separator for safe, rapid autologous PRP preparation at the point of care. Royal Wound-X, Inc. concentrates on a PRF-matrix system for rapid PRP gel preparation from peripheral blood for wound management.
These positions illustrate two strategic paths. One path concentrates on concentration performance, automation, and orthopedic or sports medicine integration, where procedural efficiency and reproducibility are paramount. The other path emphasizes wound care and regenerative applications, where matrix properties, clearance status, and reimbursement compatibility can create more defined commercial pathways. Both paths require disciplined alignment between device capability, kit economics, and clinical protocol design.
Market Evolution: Consolidation, Differentiation, and New Entry
The market is evolving along multiple axes. Consolidation pressure is rising where scale, distribution reach, and regulatory clearance create advantages, particularly in segments where procurement is centralized or where private-label distribution can rapidly expand availability. Differentiation is intensifying around workflow integration, concentration consistency, and indication-specific design, as generic autologous blood preparation becomes less distinctive in a maturing market. At the same time, new entrants continue to appear, often bringing novel spin architectures, automated separation concepts, or niche wound care formulations that challenge established incumbents on speed, yield, or use-case fit.
A notable dynamic is the increasing importance of commercial alignment beyond pure product performance. Recent developments such as exclusive private-label distribution agreements in wound care and FDA clearances for specific wound matrix indications demonstrate how regulatory milestones and channel partnerships can reshape market access. In wound care especially, clearance for exuding cutaneous wounds and diabetic or venous ulcers can materially change the commercial profile of a system by enabling more defensible positioning within reimbursement-eligible pathways. In orthopedics and aesthetics, the absence of broad coverage for many off-label applications means that competitive advantage often depends on provider education, protocol standardization, and total cost management rather than on clearance alone.
Forward Outlook: Trends Shaping the Next Three to Five Years
Trend 1: Indication-Specific Commercialization Becomes the Norm
The next phase of growth will likely reward participants that align device design, coding strategy, and clinical evidence with specific indications rather than treating PRP as a single homogeneous category. Wound care offers a concrete example: where cleared devices and defined coverage pathways exist, commercialization can be structured around documented supply chains, processing fees, and matrix-based protocols. In musculoskeletal and aesthetic settings, growth may remain stronger in cash-pay and sports medicine channels unless evidence and coding evolve further. The commercial implication is clear: companies that build indication-specific value propositions, including protocol support and billing compatibility, are better positioned to convert adoption into repeatable revenue.
Trend 2: Automation and Workflow Integration Will Separate Leaders from Laggards
Point-of-care automation, rapid preparation, and high-yield concentration are increasingly baseline expectations rather than differentiators. The next competitive frontier is end-to-end workflow integration: systems that minimize hands-on time, reduce variability, and fit cleanly into existing clinical routines. This matters because clinical adoption is often constrained by operational friction as much as by clinical interest. Manufacturers that can demonstrate reliable kit performance, straightforward preparation steps, and compatibility with institutional procurement and documentation requirements will have an advantage in converting trial use into sustained adoption.
Trend 3: Reimbursement Architecture and Cost Transparency Will Shape Segment Economics
As payers, institutions, and providers scrutinize cost, the economics of PRP will depend more heavily on coding clarity, supply-chain documentation, and processing-fee structures. Narrow coverage pathways can be commercially attractive where they are well-defined, but they also demand rigorous invoice and kit documentation. In segments where coverage is limited, cost transparency and predictable kit economics will influence whether providers continue to adopt PRP or redirect spend to alternative biologics or procedures. The risk is that uneven reimbursement and variable sterilization-driven costs create instability in margin planning and adoption forecasting.
Opportunities and Uncertainties
These trends open several commercial opportunities. There is room for differentiated systems that combine automation with application-specific performance, particularly where wound care clearance or orthopedic workflow integration can be clearly demonstrated. Distribution partnerships and private-label arrangements can accelerate access in consolidated procurement environments. There is also opportunity in standardizing kit economics and sterilization pathways to improve margin resilience. At the same time, uncertainties remain: evidence gaps in select indications, reliance on provider discretion for many off-label applications, and cost pressures from gamma sterilization and small-batch manufacturing can all temper growth expectations. Participants should also monitor regulatory developments, since device clearance does not automatically broaden coverage, and coding practices may continue to diverge across payers and regions.
Strategic Implications for Decision-Makers
For Manufacturers and Technology Developers
- Align product development with indication-specific workflow needs, prioritizing automation, reproducibility, and kit reliability over concentration claims alone.
- Invest in documentation-ready supply chains and clear billing compatibility, especially where coverage pathways such as wound care codes create structured economic models.
- Pursue distribution partnerships or private-label channels where procurement is consolidated, using cleared indications and proven reproducibility to gain entry into institutional workflows.
- Plan for cost structure resilience by standardizing single-use components, securing reliable sterilization pathways, and reducing consumable waste wherever possible.
For Investors
- Evaluate companies on the strength of their regulatory positioning, reimbursement alignment, and workflow integration rather than on market-level growth narratives alone.
- Favor business models that can convert clinical interest into repeatable economics, including recurring kit demand, stable sterilization and manufacturing pathways, and defensible channel access.
- Monitor segment-specific dynamics closely, since wound care, orthopedics, sports medicine, and aesthetics each face different evidence, coverage, and pricing constraints.
- Assess whether a company’s differentiation is durable in the face of automation becoming a baseline expectation, and whether its cost structure can withstand single-use kit economics.
For Procurement and Clinical Leaders
- Evaluate PRP systems against total cost of ownership, including kit reliability, preparation time, sterility assurance, and billing documentation requirements.
- Match system selection to the intended indication and clinical protocol, recognizing that wound care, orthopedic, and aesthetic applications often require different performance and coverage considerations.
- Require transparent documentation for supply kits, processing fees, and device clearance status to support compliance and reimbursement where applicable.
- Prioritize vendor support that includes protocol guidance, staff training, and consistent kit availability, since workflow friction can undermine adoption even when clinical interest is strong.
The PRP market is moving from broad enthusiasm to disciplined commercialization. Growth is increasingly determined by the intersection of cleared device pathways, reimbursement compatibility, workflow integration, and cost transparency. In that environment, the most valuable intelligence is segment-specific: how clearance status interacts with coding, how kit economics behave under sterilization and small-batch constraints, and where distribution partnerships can open durable access. Detailed segmentation data, competitive benchmarking, and customized scenario planning can help decision-makers translate these dynamics into concrete investment, product, and procurement choices. For leaders seeking a fuller view of the market’s subsegments, regional trajectories, and company-level positioning, accessing the complete research dataset and methodology notes provides the granularity needed to act with confidence.
For detailed analysis of this topic, please visit the official page: Platelet Rich Plasma (PRP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
ESP Market 2026–2032: Why 6.4% CAGR and Power Generation Dominance Redefine Strategy
By PW Consulting, 2026-09-21
Navigating the Electrostatic Precipitators Market: Strategic Trends and Commercial Opportunities Through 2032
The electrostatic precipitator (ESP) market is entering a phase of measured but meaningful expansion, driven by tightening emissions standards, aging infrastructure demands, and incremental technological upgrades. Between 2020 and 2025, the global market grew from 6,500.0 million USD to 8,300.0 million USD, reflecting steady demand across utility and industrial sectors. Looking ahead to the 2026-2032 forecast period, the trajectory points toward a compound annual growth rate of 6.4%, with revenue projected to reach 12,790.0 million USD by 2032. This growth is not uniform. It is concentrated among a handful of established players, as reflected in a CR3 of 38.2% and CR5 of 55.0%, indicating that scale, technical expertise, and long-term service relationships continue to shape competitive dynamics. The market’s structure favors firms that can deliver not only hardware but also lifecycle support, performance upgrades, and integration with broader emission control systems.
Behind the headline numbers lie structural tensions that will define how companies position themselves over the next several years. The first challenge centers on the balance between capital intensity and operational efficiency. Advanced ESP configurations increasingly rely on digital control modules, corrosion-resistant materials, and hybrid filtration approaches, all of which raise upfront investment. At the same time, electrical energy consumption in large-scale installations remains substantial, translating into ongoing operating costs that plant operators must justify against performance gains. The second challenge is regulatory fragmentation. While federal and regional standards continue to push particulate limits downward, the pace and specifics of compliance requirements vary by jurisdiction and by industrial application, creating uneven demand cycles and complicating long-term planning. The third challenge involves the shift from greenfield installations to retrofit and rebuild activity. Many existing plants are prioritizing incremental upgrades that restore or exceed original collection efficiency without full system replacement, reshaping procurement patterns and service expectations.
Market Structure and the Shift Toward Service-Enabled Solutions
The ESP market’s evolution is increasingly defined by how suppliers manage the entire asset lifecycle rather than by initial equipment sales alone. Rebuild contracts, performance optimization, and integration with flue gas treatment systems are gaining weight in commercial negotiations. Companies that can demonstrate consistent collection efficiency, lower operating expenditure, and predictable maintenance intervals are finding stronger positioning in both utility and industrial segments. This shift is visible in recent contract activity and network expansion moves, where the emphasis is on extending service reach, supporting existing installations, and delivering measurable efficiency improvements. For decision-makers, the implication is clear: competitive advantage is moving from hardware specification to total cost of ownership and performance reliability over time.
Key Drivers Reshaping the ESP Market
Regulatory Pressure as a Baseline Demand Catalyst
Emissions regulations are the most consistent force behind ESP demand, and recent regulatory actions reinforce that trajectory. In the United States, the EPA’s Mercury and Air Toxics Standards require coal-fired power plants to contain filterable particulate emissions at 0.03 lb/MMBtu, accelerating the deployment of ESP systems that can meet or exceed those limits. At the same time, federal regulations on particulate matter emissions from industrial sources continue to compel facilities to adopt ESP technologies for compliance. These requirements do not merely create one-time purchase cycles; they establish a compliance floor that encourages operators to invest in systems capable of sustained performance, particularly where future tightening is anticipated. For suppliers, this environment rewards proven high-efficiency collection capability and the ability to document compliance outcomes.
Technological Innovation: Efficiency, Control, and Integration
Technological progress in ESP systems is increasingly focused on improving collection efficiency while moderating energy use and simplifying integration with downstream gas cleaning. High-efficiency collection up to 99.9% is now a benchmark that several leading providers reference, and achieving that level consistently often depends on advanced electrode design, better discharge management, and refined control logic. Equally important is the move toward smarter operation. AI-enhanced control systems and digital monitoring are being embedded into ESP platforms to adjust operating parameters in response to load changes, dust characteristics, and process conditions. This reduces wasted energy, stabilizes performance, and improves predictability for plant operators. Integration with flue gas conditioning and NOx reduction technologies further extends the value of ESP installations, especially in coal-fired utility settings where multi-pollutant control is a priority.
Recent developments illustrate how these innovations are being commercialized. Babcock & Wilcox secured more than 18 million USD in wet and dry ESP rebuild contracts for utility and industrial plants across the U.S. and Europe, emphasizing collection efficiency up to 99.9%, a clear signal that performance-led upgrades remain commercially attractive. FLSmidth expanded its service center network with a new facility in Dammam, Saudi Arabia, to support advanced emission control technologies including electrostatic precipitators, reflecting a strategy of positioning service capability closer to key industrial demand centers. Mitsubishi Heavy Industries delivered an ESP unit for a 700,000-tonne chemical pulp project in China, while Valmet shipped electrostatic precipitators to Nordic Paper’s Swedish Backhammar recovery boiler with completion targeted by the end of 2025. These activities show that demand is not limited to power generation; pulp and paper, chemical pulp production, and broader industrial recovery systems are also active deployment areas where ESP performance matters.
Demand-Side Shifts Across Power and Industrial Applications
Demand for ESP systems continues to be anchored by power generation, particularly where coal-fired and biomass-linked facilities must meet strict particulate limits or extend the viable operating life of existing assets. Beyond power, industrial applications are expanding the addressable market. Cement and lime processing, waste-to-energy and biomass, chemical and petrochemical operations, and specialized sectors such as pulp and paper recovery boilers all present distinct dust characteristics and operating conditions that shape ESP selection. The commercial implication is that a single ESP architecture rarely fits all applications. Suppliers that can tailor electrode design, gas flow management, and cleaning methods to specific process environments are better positioned to capture demand across multiple verticals. This is also where wet and dry system choices become strategically important, with selection driven by dust properties, moisture content, and downstream process constraints.
PW Consulting
Cost, Energy, and Supply Chain Considerations
Despite the positive demand outlook, cost and energy dynamics remain central to commercial decision-making. High capital and maintenance costs for advanced ESP systems incorporating digital control modules, corrosion-resistant materials, and hybrid filtration technologies require substantial upfront investment. Electrical energy consumption in electrostatic precipitators can also be substantial, with resulting high operating costs for large-scale installations. These factors encourage a more disciplined approach to procurement, where operators evaluate not only collection performance but also energy profile, maintenance intervals, and 부품 or material availability over the system’s lifespan. Supply chain considerations are becoming more prominent as well, particularly for specialized materials and control hardware. Providers that can streamline sourcing, localize support, and reduce downtime through predictable maintenance planning are likely to gain preference in competitive bidding situations.
Competitive Landscape and How Leading Players Differentiate
The ESP market is moderately concentrated, with a limited group of established companies holding meaningful share and long-standing relationships across utility and industrial markets. Market leadership is less about unit volume alone and more about the breadth of application coverage, demonstrated efficiency, service reach, and the ability to offer integrated emission control solutions. Several firms have built their positioning around high-efficiency systems, rebuild and retrofit capabilities, and sector-specific expertise. For example, some leaders emphasize wet and dry ESP systems for utility and industrial power generation with global installation experience, while others specialize in advanced ESP technologies integrated with gas cleaning systems for industrial emission control. Custom wet and dry ESP manufacturing for power, cement, and steel applications remains a differentiator for firms serving heavy industrial environments, and AI-enhanced control systems are increasingly part of the value proposition for providers targeting cement and industrial applications.
Worldwide Dry Electrostatic Precipitator Market
Company activity over the past two years highlights three strategic themes. First, performance-led rebuilds are a commercially meaningful pathway, as shown by major rebuild contracts focused on restoring or improving collection efficiency in existing plants. Second, geographic and service expansion is being used to reduce response times and strengthen relationships in important demand regions, including the Middle East. Third, sector-specific project wins in pulp, chemical pulp, and recovery boiler environments indicate that specialization can open doors beyond the largest power generation markets. Together, these moves suggest a market where incumbents are reinforcing their positions through service proximity, proven efficiency claims, and application-specific execution rather than relying solely on equipment pricing.
Consolidation, Fragmentation, and Entry Dynamics
The ESP market is not experiencing dramatic consolidation at the top, but it is showing signs of functional consolidation around capabilities. Buyers increasingly value suppliers that can handle design, installation, commissioning, and ongoing optimization under a coordinated framework. At the same time, niche players remain relevant where specialized applications, local support needs, or custom engineering demands create room for focused offerings. New entry is challenging but not impossible, especially where a company brings a clear technical advantage, such as a novel control approach, improved energy management, or a distinctive material solution that lowers lifecycle cost. In practice, the most resilient competitors are those that combine technical credibility with commercial flexibility, allowing them to serve both large-scale utility projects and smaller industrial retrofits without losing operational focus.
Forward Outlook: Trends Likely to Shape the Next 3-5 Years
Trend 1: Efficiency and Energy Management Will Become the Central Battleground
As regulations tighten and operating costs remain under scrutiny, the most important competitive differentiator will be the ability to deliver high collection efficiency without inflating energy consumption. Systems that can modulate power use intelligently, sustain efficiency across variable loads, and integrate with broader plant controls will be favored in both new installations and upgrades. This trend creates commercial opportunities for providers that can quantify energy savings, reduce maintenance burden, and show compliance durability over time. It also raises the stakes for suppliers still relying on static operating profiles, since plants are increasingly reluctant to accept high operating costs as a fixed requirement.
Electrostatic Chucks (ESCs) Market
Trend 2: Retrofit, Rebuild, and Life Extension Will Outweigh Greenfield Demand in Many Markets
In many regions, the near-term opportunity lies less in replacing entire systems and more in restoring performance, adapting to new fuel or process conditions, and extending service life. Rebuild contracts and targeted upgrades are likely to remain a significant share of activity, especially where plants need to meet current standards or prepare for future limits without committing to full replacement. This shift rewards vendors with strong field service capabilities, modular upgrade paths, and the ability to diagnose existing installations efficiently. For investors and manufacturers, it suggests that service-oriented revenue streams and upgrade kits may be as strategically important as flagship new-system sales.
Trend 3: Regional Service Footprints and Application Specialization Will Determine Access to Demand
Demand is geographically and sectorally uneven, and access to projects will increasingly depend on local presence and application knowledge. Expansion of service centers, local support teams, and region-specific engineering capacity can reduce friction in procurement and commissioning while improving responsiveness during operation. At the same time, companies that understand the dust and process nuances of specific industries will be better positioned to win in segments such as cement, waste-to-energy, chemical, and pulp and paper applications. The commercial opportunity here is to build repeatable sector playbooks rather than treating each project as a standalone customization exercise.
Risks and Uncertainties to Monitor
Several uncertainties could alter the pace or shape of market growth. Regulatory timelines may shift, particularly if compliance deadlines are adjusted or if enforcement emphasis changes across jurisdictions. Energy pricing and availability can affect operating economics, especially for large installations where power use is a major cost element. Material availability and lead times for specialized components may influence project scheduling and total cost. Finally, changes in fuel mix, plant retirement decisions, and the balance between coal, biomass, and alternative generation pathways can reshape where ESP demand appears and how quickly it materializes. Companies that monitor these variables closely will be better prepared to adjust pipeline planning and service capacity.
Strategic Recommendations for Decision-Makers
For ESP Manufacturers and Solution Providers
- Prioritize total-cost-of-ownership positioning by documenting efficiency outcomes, energy behavior, and maintenance predictability, not just collection performance at a point in time.
- Invest in service and rebuild capabilities, since retrofit and upgrade activity is likely to remain a durable source of revenue and customer contact.
- Build application-specific engineering playbooks for cement, waste-to-energy, chemical, and pulp and paper environments, where process conditions shape system selection and value claims.
For Investors and Strategic Partners
- Evaluate providers based on their ability to sustain high-efficiency claims in the field, expand service reach, and capture multi-pollutant integration opportunities rather than equipment scale alone.
- Watch for commercial signals in rebuild activity, regional service expansion, and sector project wins, as these often indicate where demand is becoming more concrete.
- Assess exposure to energy-intensive operating profiles and specialized material supply, since these factors influence margin stability and project execution risk over the forecast period.
For Plant Operators and Procurement Teams
- Select ESP solutions with a clear view of lifecycle cost, including energy consumption, maintenance intervals, and the feasibility of future upgrades as regulations or processes change.
- Use rebuild and retrofit pathways where feasible to meet current compliance targets while preserving capital flexibility for other plant priorities.
- Request performance evidence tied to operating conditions similar to your own, especially for dust characteristics, load variability, and integration with existing gas treatment systems.
The ESP market is moving toward a more performance-intensive, service-oriented, and application-aware phase of growth. That shift rewards companies that can combine proven collection efficiency with smarter operation, local support, and credible lifecycle economics. For organizations seeking to navigate this environment with greater precision, deeper segmentation data, company-level benchmarks, and customized strategic guidance can clarify where to commit resources and how to sequence next steps. Access the full PW Consulting report on the Electrostatic Precipitators market to explore detailed segmentation, competitive profiles, and forward-looking scenarios built for planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Electrostatic Precipitators (ESP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Chemotherapy Induced Peripheral Neuropathy Treatment Market: 6.5% CAGR from 2026-2032
By PW Consulting, 2026-09-21
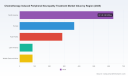
Chemotherapy-Induced Peripheral Neuropathy Treatment Market: Strategic Trends and Commercial Opportunities
The chemotherapy-induced peripheral neuropathy (CIPN) treatment market has reached a critical inflection point. With a total market value of approximately $1.46 billion in 2025 and a projected trajectory to exceed $2.28 billion by 2032, the sector reflects a compound annual growth rate of 6.5 percent over the 2026-2032 period. This expansion is not merely a function of rising oncology volumes. It represents a structural shift in how the pharmaceutical industry approaches symptom management, neurological preservation, and quality-of-life endpoints in cancer care. Chemotherapy remains one of the most widely deployed modalities in oncology, and neuropathy stands among its most persistent and debilitating side effects. Patients receiving platinum-based agents, taxanes, and vinca alkaloids frequently experience progressive sensory loss, pain, balance impairment, and treatment-limiting dose reductions. The market for interventions addressing these outcomes has evolved from a fragmented landscape of off-label symptomatic therapies into a structured pipeline of mechanism-targeted candidates, increasingly shaped by regulatory guidance and clinical evidence standards.
Yet the scale of opportunity is matched by complexity. Stakeholders approaching this space must navigate a market where clinical differentiation, regulatory pathways, pricing dynamics, and oncology practice patterns intersect in non-linear ways. The next phase of growth will likely reward players who can translate mechanism plausibility into robust trial design, align with evolving oncology workflows, and articulate value propositions that resonate beyond symptom relief alone. Understanding where the market stands today, what forces are reshaping it, how competitors are positioning themselves, and where strategic opportunities are likely to emerge provides a necessary foundation for informed decision-making.
Market Landscape and Core Challenges
The CIPN treatment space is characterized by moderate market concentration and a therapeutic mix that still leans heavily on existing symptomatic classes, particularly antidepressants and anticonvulsants, alongside a smaller but strategically important segment of narcotics and emerging alternatives. This composition reflects both historical prescribing habits and the limited number of approved, mechanism-specific interventions. While the broader market size demonstrates steady expansion, the underlying structure reveals a sector that is simultaneously mature in its standard-of-care elements and early-stage in its innovation pipeline. That duality creates both stability and uncertainty, as legacy therapies continue to anchor clinical practice while newer candidates attempt to redefine therapeutic expectations.
A first challenge lies in clinical endpoint definition and trial design. CIPN presents across a spectrum of sensory, motor, and autonomic symptoms, and the field has historically struggled to standardize how improvement, stabilization, or prevention should be measured. Different chemotherapy regimens, cumulative dosing patterns, and patient baseline risk profiles complicate the creation of uniform trial populations. Sponsors that rely on broad symptom scales without mechanistic alignment or clearly defined responder thresholds risk generating data that is difficult to position clinically or commercially. The challenge is not simply demonstrating statistical change. It is demonstrating clinically meaningful change that oncologists, neurologists, and payers can act upon.
A second challenge is the persistent alignment gap between existing symptomatic classes and the underlying neurobiology of nerve injury. Current treatments often address perceived symptom pathways without directly interrupting axonal degeneration, ion channel dysfunction, or inflammatory signaling associated with specific chemotherapeutic agents. As understanding of CIPN mechanisms matures, therapies that are not linked to a plausible biological rationale may face growing pressure in clinical discussion and formulary positioning. This does not render all symptomatic options obsolete, but it does raise the bar for differentiation. The market increasingly favors interventions that can articulate not only what they treat, but why they should work in a particular chemotherapy context.
PW Consulting Health Care Research Center
A third challenge involves the oncology treatment environment itself. Dose adjustments, regimen substitutions, and individualized risk-benefit calculations can influence both the incidence of neuropathy and the perceived value of adjunctive interventions. In practice, neuropathy management does not exist in isolation. It competes for attention alongside tumor response, survival endpoints, and other supportive care priorities. Treatments that can integrate into existing oncology workflows, offer predictable safety profiles, and demonstrate a credible link to preserving chemotherapy delivery are more likely to gain adoption than those positioned as standalone neurological interventions with limited integration into cancer care pathways.
Key Drivers Shaping the Market
Several interconnected factors are accelerating momentum in the CIPN treatment market, and their influence is likely to intensify over the next several years. Rather than acting independently, these forces are reinforcing one another, reshaping both pipeline priorities and commercial expectations.
One of the most consequential drivers is the shift toward mechanistic and targeted approaches. A growing portion of the pipeline is focused on molecular pathways with clearer links to nerve injury, signaling dysregulation, or peripheral nerve repair. Candidates addressing specific ion channels, receptor-mediated protective pathways, and topical delivery strategies reflect an effort to move beyond nonspecific symptom modulation. This trend matters commercially because it creates opportunities for sharper messaging, more defensible clinical narratives, and potential differentiation in a crowded supportive care environment. At the same time, it raises the technical requirement for biomarker strategy, subgroup definition, and endpoint clarity. Sponsors that can connect a mechanism to a meaningful clinical readout are better positioned to justify investment and partnership interest.
Regulatory guidance and pathway signals are a second major driver. The issuance of FDA draft guidance for developing drug and biological products for the prevention and treatment of CIPN has helped establish a more explicit framework for expectations around trial design, population definition, and outcome measurement. Complementary regulatory actions, including Fast Track designations and IND clearances for candidates targeting CIPN, indicate that the agency is engaging with the area more actively. This environment reduces some ambiguity for developers and can improve the perceived credibility of programs that are designed with regulatory expectations in mind. For commercial stakeholders, the implication is that programs aligned early with guidance are more likely to navigate development with fewer late-stage surprises and clearer dialogue with regulators.
A third driver is the changing demand profile within oncology. As cancer therapies improve and patients live longer, the burden of chronic treatment-related effects is becoming more visible. Neuropathy that persists beyond active chemotherapy or limits future treatment options carries significant downstream implications for physical function, independence, and quality of life. This has increased attention to interventions that can prevent symptomatic progression, reduce dose-limiting toxicity, or support patients through longer treatment courses. Demand is not only coming from patient advocacy and clinician concern. It is also being shaped by the broader oncology goal of preserving treatment continuity and minimizing long-term functional impairment.
Supply-side and reimbursement dynamics also play a role, though often in less visible ways. The relative availability of generic symptomatic therapies exerts competitive pressure on pricing and adoption for newer agents, while reimbursement expectations increasingly favor evidence that connects treatment to functional outcomes, reduced downstream costs, or maintained chemotherapy delivery. Cost structures are therefore influenced by both the competitive shadow of established options and the evidentiary requirements of payers and health systems. Programs that can demonstrate practical value in real-world oncology settings are more likely to achieve sustainable market positioning than those relying solely on clinical signals without integration into care economics.
Competitive Landscape and Leading Strategies
The competitive environment reflects a spectrum of developmental maturity and strategic focus. Some companies are advancing candidates with clearer regulatory momentum or later-stage clinical activity, while others are operating in earlier phases or have paused further development after earlier signals. What distinguishes the more strategically positioned players is not only the stage of their programs, but the coherence of their therapeutic rationale, the alignment of their trial design with oncology context, and their ability to use regulatory or partnership leverage to accelerate confidence in their approach.
Dogwood Therapeutics illustrates a company building momentum through a combination of clinical progress and strategic licensing activity. The Halneuron program has moved forward in Phase 2b with reported interim findings and substantial enrollment progress, while the SP16 program has advanced through licensing from Serpin Pharma with IND clearance and planned Phase 1b activity. This dual-track structure suggests an emphasis on diversifying mechanism exposure while maintaining forward progress in a lead candidate. From a strategic standpoint, the company appears to be positioning around both clinical data generation and partnership-enabled capability expansion, which can be valuable in a market where single-asset dependence carries execution risk.
Asahi Kasei Pharma’s ART-123 program takes a prevention-oriented approach in a defined oncology population, focusing on sensory symptom prevention in colorectal cancer patients receiving oxaliplatin. This positioning is strategically notable because prevention can be harder to demonstrate than treatment, but it may also offer stronger clinical integration if the evidence supports a clear reduction in neuropathy burden within a specific chemotherapy context. Targeting a well-defined regimen and patient group can reduce some of the heterogeneity challenges that complicate broader CIPN studies, though it also narrows the initial commercial footprint.
Neuropathy Pain Treatment Market
Sironax’s SIR2501 program has drawn attention through Fast Track designation, signaling regulatory recognition of potential unmet need and development efficiency value. In a market where endpoint complexity can slow progress, regulatory designations can provide useful leverage for development planning, clinical engagement, and partnership conversations. WinSanTor’s topical pirenzepine program, meanwhile, reflects an alternative delivery strategy and a broader peripheral neuropathy focus, with ongoing work extending beyond CIPN. Topical approaches may be attractive if they can reduce systemic exposure or offer localized benefit, but adoption will depend on evidence that supports clinical differentiation and practical usability.
Serpin Pharma’s SP16 program reinforces the growing importance of early-stage financing and academic or institutional support in shaping pipeline viability. The receipt of grant funding to support a Phase 1b trial highlights how non-dilutive resources can help earlier programs reach critical developmental checkpoints. For investors and partners, this is a reminder that the CIPN market includes meaningful activity not only from large-scale commercial developers, but also from smaller, mechanism-focused groups whose evolution may influence future licensing and acquisition dynamics.
Across these players, a few competitive themes emerge. First, there is a clear trend toward programs that are more tightly tied to specific mechanisms or delivery modalities, with the intent of differentiating from nonspecific symptom management. Second, regulatory engagement and guidance alignment are increasingly part of strategic positioning, particularly for companies looking to reduce development risk or improve the credibility of their programs in clinical and investor discussions. Third, the landscape remains open enough for new entrants to find niches, but crowded enough that differentiation must be supported by more than mechanistic plausibility. Credible clinical design, context-specific positioning, and practical integration into oncology care will likely determine which programs translate into durable commercial advantage rather than short-term pipeline interest.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, several trends are likely to shape the direction of the CIPN treatment market. These are not mutually exclusive, and each carries distinct commercial implications.
One likely trend is a sharper separation between prevention-focused and treatment-focused interventions. As clinical programs mature, stakeholders may increasingly differentiate between agents intended to reduce the onset or progression of neuropathy during chemotherapy and those intended to manage established symptoms. This distinction matters for trial design, regulatory positioning, and clinical adoption. Prevention programs may target specific regimens or high-risk populations, while treatment programs may need to demonstrate meaningful benefit in patients with existing neurological impairment. The commercial implication is that value propositions will need to be tailored more precisely to the clinical context in which the intervention is used. Broad, undifferentiated claims may be less effective than narrowly supported, use-case-specific positioning.
A second trend is the increasing importance of topical and targeted delivery approaches alongside systemic therapies. Topical strategies may gain attention if they can offer focused benefit with favorable tolerability or reduced systemic exposure, especially in a population where polypharmacy and cumulative toxicity are concerns. However, clinical adoption will depend on whether these approaches can demonstrate consistent efficacy, ease of use, and integration into oncology supportive care routines. The commercial opportunity is not just in developing a new formulation. It is in proving that the delivery method creates meaningful clinical or operational advantages that clinicians and patients will accept in practice.
A third trend is growing pressure to connect CIPN interventions with functional and care-continuity outcomes. As payer and health system expectations evolve, evidence that goes beyond symptom scores may become more important. Demonstrating associations with maintained chemotherapy dosing, reduced supportive care utilization, or improved day-to-day function could strengthen commercial viability for certain programs. The risk is that companies relying solely on conventional symptom endpoints without a clear link to broader outcomes may find adoption more difficult or reimbursement discussions more complex. This creates a strategic imperative to design evidence generation around the full clinical and economic context of use.
At the same time, uncertainty remains. Trial results may vary by chemotherapy class, baseline risk, and endpoint definition, and not every mechanistic hypothesis will translate into durable clinical benefit. Competitive dynamics may also shift through partnerships, licensing, or consolidation, particularly as earlier-stage programs reach pivotal milestones. Stakeholders should therefore plan for a market that is growing but fragmented in credibility, where selection of partners, programs, or investment targets requires careful assessment of trial design, intended use case, and alignment with oncology practice.
Strategic Recommendations for Decision-Makers
For manufacturers and developers, the priority is to design programs with clear clinical context and regulatory alignment from the outset. This includes defining the intended chemotherapy setting, the relevant patient population, and the endpoint strategy in a way that supports both clinical credibility and commercialization. Mechanism-based differentiation is valuable, but it must be paired with evidence that can withstand scrutiny in real-world oncology settings. Developers should also consider how they will position their intervention relative to existing symptomatic options and whether they can articulate a distinct value proposition around tolerability, delivery, or care integration.
For investors, the opportunity lies in distinguishing programs with defensible execution roadmaps from those that depend primarily on early enthusiasm. Attention should be paid to enrollment feasibility, endpoint clarity, regulatory engagement, and the strength of clinical rationale within a specific chemotherapy context. Programs that combine mechanism interest with sound trial design and credible milestones may offer stronger risk-adjusted prospects than those that emphasize scientific promise without a clear path to clinically actionable evidence. Early-stage licensing and partnership activity may also create optionality, particularly if it enables better-capitalized or more operationally experienced groups to accelerate development.
For procurement and formulary decision-makers, the focus should be on evidence that supports practical adoption and value relative to current care patterns. This means evaluating not only efficacy signals but also safety, ease of integration, and any demonstrated impact on treatment continuity or functional outcomes. As new agents emerge, structured assessment frameworks can help determine which interventions warrant adoption, under what conditions, and where further evidence is needed before broader use. The availability of more standardized guidance and maturing clinical data should support more disciplined evaluation over time.
Worldwide Advanced Cancer Pain Management Market
In a market expanding toward $2.28 billion by 2032, the strategic question is not whether demand for effective CIPN intervention will continue to grow, but which programs, partnerships, and evidence strategies will separate durable value creation from transient pipeline interest. Detailed segmentation data, pipeline benchmarking, and scenario analysis can help organizations move from general market awareness to specific, actionable decisions. Readers interested in deeper breakdowns of market segments, competitive benchmarks, and customized strategic implications can explore the full report available through PW Consulting for more detailed segmentation data and tailored guidance.
For detailed analysis of this topic, please visit the official page: Chemotherapy Induced Peripheral Neuropathy Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Insect Feed Market: How 16.4% CAGR and Aquaculture Demand Reshape 2032 Outlook
By PW Consulting, 2026-09-21
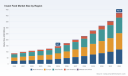
The Insect Feed Market: Strategic Trends and Commercial Opportunities Through 2032
The insect feed sector is transitioning from niche sustainability play to mainstream protein infrastructure. With the global market valued at approximately $147 million in 2025 and projected to reach $425.8 million by 2032, the sector is expanding at a compound annual growth rate of 16.4 percent. This trajectory reflects more than incremental demand growth. It signals a structural recalibration of animal nutrition supply chains, driven by regulatory opening, substrate economics, and the scaling of bioconversion technology. For executives and investors, the question has shifted from whether insect protein will gain traction to how capital, capability, and partnerships will be allocated as the market matures.
Market Landscape and Core Challenges
The revenue arc over the past half-decade illustrates steady acceleration, with growth compounding as production capacity converts from pilot scale to commercial throughput. By the close of the forecast window, the market is on a path toward nearly triple its 2025 baseline. That expansion is uneven rather than uniform, shaped by regional regulatory readiness, feed formulation economics, and the pace at which manufacturing networks achieve cost parity with conventional protein sources. Understanding where the market is heading requires looking past headline figures to the structural constraints that will determine which players capture value.
Navigating Structural Constraints
Several inflection points are shaping the operational reality of the industry. First, substrate sourcing and waste-stream consistency remain foundational bottlenecks. Insect feed production depends on upcycled organic inputs such as food processing byproducts, and the economics of collection, pretreatment, and contamination control vary widely by geography and season. While this model can reduce material costs substantially relative to conventional protein sourcing, the operational discipline required to maintain consistent substrate quality across multiple intake streams is non-trivial. Facilities that fail to standardize input quality encounter downstream variability in yield, nutrient profiles, and regulatory compliance.
Second, regulatory adoption is advancing but remains fragmented. In the European Union, rules governing insect protein in aquaculture are established, and approval pathways for poultry and swine applications have progressed under updated feed frameworks. In the United States, regulatory clearances have extended for select insect proteins in poultry and pet food categories. The pace and scope of these approvals differ by jurisdiction and protein type, creating uneven commercialization timelines. Companies that can navigate multiple regulatory regimes simultaneously, or that align product development with the fastest-opening categories, gain a meaningful time advantage.
Aqua Feed Market
Third, scaling biology is as much an engineering challenge as a biological one. Temperature control, humidity management, disease mitigation, and harvesting logistics all influence yield stability and unit economics. Early-stage producers often underestimate the capex intensity of climate-controlled environments and the operational complexity of continuous rearing systems. As the market moves toward larger facilities, the gap between companies with proven process control and those still refining biological workflows will become more visible in margin performance and supply reliability.
Key Drivers Reshaping the Sector
Several forces are converging to accelerate adoption and reshape competitive dynamics. These drivers are not isolated; they reinforce each other and create a clearer line of sight to commercial scale for operators who align technology, compliance, and customer demand.
Bioconversion and Process Technology
The most consequential technical progress lies in improving rearing efficiency, feedstock flexibility, and downstream processing consistency. Proprietary rearing systems, automation in harvesting and separation, and process controls that stabilize larval growth cycles are reducing variability in protein and lipid outputs. This matters because feed formulators require repeatable nutrient profiles, contamination thresholds, and functional properties. Companies that treat insect production as a manufacturing process rather than an agricultural experiment are gaining credibility with B2B buyers who evaluate suppliers on reliability as much as sustainability credentials.
The commercial significance of this shift is clear when viewed alongside recent market activity. Innovafeed has expanded its operational footprint with a U.S. facility in Decatur, Illinois, marking a step toward localized production in a market where feedstock availability and regulatory timing support scale-up. This move illustrates how technology-enabled producers are positioning themselves closer to end markets in order to reduce logistics friction and respond more quickly to regional demand signals.
Regulatory Opening and Category Expansion
Regulation remains the central gatekeeper for category expansion. Approvals for aquaculture have already enabled commercial use of insect proteins in fish feed, while newer regulatory movements in the EU and U.S. have extended possibilities into poultry and swine nutrition and, in certain contexts, pet food. These changes do not merely open new addressable segments; they reshape feed formulation economics by creating alternatives to soy and fishmeal in categories where substitution pressure is strongest.
The regulatory trajectory also influences procurement behavior. Feed manufacturers and integrators that have been waiting for regulatory clarity are now beginning to test inclusion rates, evaluate supply continuity, and negotiate multi-year arrangements. Protix, for example, signed a multi-year supply agreement with Skretting for black soldier fly meal in salmon feed formulations, a move that signals how regulatory maturity is translating into committed offtake and category-specific product development.
Demand-Side Shifts in Animal Nutrition and Pet Care
Demand is being pulled by multiple end-use pressures. In aquaculture, the need for sustainable protein inputs continues to intensify as marine ingredient supply faces volatility and environmental scrutiny. In poultry and swine nutrition, producers are exploring insect protein not only for sustainability positioning but also for functional benefits and supply diversification. In pet food, consumer interest in novel protein sources and premium formulation is expanding the addressable market for insect-based ingredients, particularly where regulatory clearance and brand acceptance progress together.
This diversification matters strategically because it reduces dependence on any single category’s adoption cycle. Companies with portfolios that span aquaculture, livestock nutrition, and pet food can shift commercialization emphasis as regulatory timing and customer readiness vary by region. The effect is a more resilient demand base and a stronger foundation for long-term contract structures.
Cost Structure and Substrate Economics
The economic case for insect feed is closely tied to substrate cost and plant efficiency. Because insect production can utilize upcycled organic waste streams, input costs can be materially lower than those of conventional protein sources when collection and pretreatment are managed effectively. Life cycle assessments comparing insect-based inputs with soy or fishmeal indicate substantial differences in land and water requirements and lower associated greenhouse gas emissions, reinforcing the sustainability narrative that supports procurement decisions.
However, cost advantage is not automatic. It depends on logistics networks, preprocessing capability, and the ability to maintain consistent substrate composition at scale. Facilities that integrate substrate procurement, pretreatment, and rearing into a coordinated operational model are better positioned to protect margins as volumes increase. This is where competitive differentiation increasingly emerges: not simply in the insect species used, but in the industrial design of the entire value chain.
Competitive Landscape and Leading Strategies
The market remains moderately concentrated, with a small group of established producers accounting for a meaningful share of revenue and an expanding set of regional and specialized entrants competing on niche formulations, geography, or substrate strategies. The strategic posture of leading companies reveals how value is being captured in a market still defining its standards.
Differentiation Through Scale, Technology, and Of ftake
Several patterns distinguish the more advanced players. Protix has built a profile around high-quality insect solutions spanning feed, pet food, aquaculture, and plant care, with a focus on black soldier fly larvae and broad application coverage. Its multi-year agreement with Skretting illustrates a strategy centered on committed customer relationships and category-specific formulation support, which helps stabilize demand and fund capacity expansion.
Innovafeed has emphasized proprietary rearing technology and geographic expansion, including its U.S. facility in Illinois. This reflects a strategy of combining technical differentiation with direct market access, reducing reliance on export logistics and positioning closer to large North American feed markets. Entobel has pursued a similar operational discipline, with long-standing production in Vietnam and a recent certification milestone that reinforces its positioning around sustainability and governance as commercial signals for B2B buyers.
Pet Food Insect Protein Market
Other companies are carving distinct lanes. Beta Hatch has focused on mealworm-based production within a regenerative agriculture framing, highlighting a different species and system design from the black soldier fly-dominant core of the market. Nutrition Technologies, now operating under the Sentara Group name following expansion, has continued to build around black soldier fly ingredients for aquaculture, agriculture, and animal feed, illustrating how rebranding and organizational scaling can accompany capacity growth. Hexafly and nextProtein have emphasized the bioconversion of food waste into protein, oil, and fertilizer, aligning product portfolios with circular-economy value propositions that appeal to customers seeking integrated sustainability outcomes.
Market Evolution: Consolidation, Specialization, and New Entry
The competitive landscape is evolving along several axes. Scale industrialization is concentrating production among companies able to fund large facilities, standardize processes, and secure stable substrate supply. At the same time, specialization remains viable in niches such as pet food formulations, functional ingredients, plant care products, and regional supply arrangements where logistics and regulatory timing favor local production.
New entry continues, but the bar is rising. Early entrants could often compete on concept and pilot output; newer entrants must demonstrate process reliability, regulatory compliance, cost control, and defensible customer relationships. This dynamic is likely to reward operators that combine biological capability with manufacturing discipline and commercial execution. It also suggests that partnerships, offtake agreements, and integration with existing feed supply chains will become more important than standalone brand positioning.
Forward Outlook: Three Strategic Trends for 2026–2032
Looking ahead, several trends are likely to define how value accrues in the insect feed market over the next several years.
Trend 1: Regional Production Clusters and Feedstock-Proximity Manufacturing
Production is likely to consolidate around feedstock availability, regulatory readiness, and end-market demand rather than forming a single global center of gravity. Regions with strong waste-stream infrastructure, supportive feed regulations, and large aquaculture or livestock sectors will attract capacity. This has direct commercial implications: companies that align facility siting with substrate economics and customer proximity will lower logistics costs and improve supply reliability, while those dependent on long-distance substrate or product movement may face margin pressure as the market scales.
Trend 2: Formulation Integration and Category-Specific Product Design
Insect ingredients will increasingly be valued not simply as generic protein but as formulated inputs tailored to specific species, life stages, and functional requirements. As feed manufacturers gain experience with inclusion rates and nutrient performance, demand will shift toward consistent specifications, traceability, and technical support. The commercial opportunity lies in building product architectures around customer formulations rather than selling undifferentiated bulk ingredients. Suppliers that invest in application engineering and quality assurance will be better positioned to defend pricing and deepen relationships.
Trend 3: Regulatory Normalization and Procurement Mainstreaming
As approvals expand and standards mature, insect protein is likely to move from special-case procurement to routine supplier evaluation. That transition will favor operators with established compliance records, auditable quality systems, and supply continuity. It also introduces risk: regulatory timing can shift, inclusion limits can change, and category approvals may not proceed uniformly. Companies that assume a linear regulatory path without scenario planning may misallocate capacity or overcommit to segments that open more slowly than expected.
Associated uncertainties include substrate consistency at scale, biological process control during rapid expansion, and the risk that sustainability narratives alone will not sustain procurement decisions if cost or performance gaps remain. The market’s trajectory is strong, but execution quality will determine which participants convert growth into durable margins.
Implications and Actions for Decision Makers
For executives and investors evaluating the insect feed market, the strategic task is to match ambition with operational readiness and to prioritize the decisions that convert market momentum into competitive advantage.
PW Consulting Health Care Research Center
For Producers and Technology Developers
- Prioritize process control and substrate logistics as the foundation of scale-up. Consistent quality and cost stability matter more to B2B buyers than incremental sustainability claims, so investment should flow toward rearing consistency, harvesting efficiency, and integrated feedstock management.
- Align capacity deployment with regional regulatory timing and customer demand. Expanding too quickly into segments with uncertain approval pathways can create underutilized assets, while sequencing expansion around opening categories supports revenue absorption and learning-curve gains.
- Build formulation support and application data. As customers move from trial to routine use, technical service capability becomes a differentiator. Developing species-specific and application-specific evidence strengthens customer retention and pricing power.
For Investors and Capital Allocators
- Evaluate biological capability alongside manufacturing discipline. The most attractive opportunities are likely to be with teams that can demonstrate repeatable yield, contamination control, and cost trajectory rather than concept-level promise.
- Assess demand visibility through offtake structure and customer diversification. Contracts, pilot-to-commercial conversion rates, and exposure across aquaculture, livestock, and pet food can indicate resilience if one category’s adoption slows.
- Model regulatory and substrate scenarios, not just base-case growth. Because approvals, inclusion limits, and feedstock availability can vary by region, sensitivity analysis around timing and input costs is essential for realistic return expectations.
For Procurement and Feed Formulators
- Treat insect ingredients as part of a supply diversification and sustainability strategy, but validate them through performance trials and supply reliability assessment. The strategic value lies in reducing exposure to conventional ingredient volatility while maintaining nutrient specification and consistency.
- Engage early with suppliers on specification design and traceability. Collaboration on inclusion rates, quality parameters, and auditability can accelerate integration and reduce reformulation risk.
- Structure sourcing with regulatory awareness. Procurement plans should account for category-specific approvals and potential changes in inclusion limits so that supply commitments align with regulatory reality in each market.
Closing Perspective
The insect feed market is entering a phase where growth is increasingly determined by execution rather than narrative. The revenue trajectory through 2032 points to a substantial expansion in addressable demand, but the distribution of value will depend on how effectively companies manage substrate economics, regulatory complexity, process control, and customer integration. For organizations building, funding, or sourcing from this sector, the opportunity is not simply to participate in a high-growth category but to shape a supply chain that can deliver consistent quality at competitive cost while meeting the sustainability expectations of modern animal nutrition. Detailed segmentation, regional dynamics, and company-level benchmarking can sharpen these decisions further, and a full research report can provide the supporting data and structured frameworks needed for planning at the segment and facility level.
For detailed analysis of this topic, please visit the official page: Insect Feed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com